Author: mdimdadulhaq10@gmail.com

  • 3D Secure Explained: Why Your Bank Asks for Codes Online

    3D Secure Explained: Why Your Bank Asks for Codes Online


    Example scenario: you’re paying for a software plan, the checkout page goes gray and a box from your bank asks for a code sent by text. The text never comes. You request another, the box times out, and the merchant shows “3D Secure verification failed.” Your card has money on it and works in shops, so what went wrong?

    3D Secure is the extra check behind those bank pop-ups and app prompts. Most of the time you never see it. When you do and it fails, the error message rarely explains why. This guide covers how 3D Secure works, the common reasons a 3D Secure check fails, a step-by-step fix list, and when to stop retrying and call your bank.

    What 3D Secure is

    3D Secure (3DS) is an authentication standard for online card payments. The card networks run their own programs on it: Visa Secure, Mastercard Identity Check and American Express SafeKey. Its job is to confirm that the person paying is the cardholder before the payment is authorized. In Europe and the UK, strong customer authentication rules mean many online payments must be verified this way, so European shoppers see it often.

    How a 3D Secure check works

    Three parties are involved: the merchant, the card network’s 3DS system, and your bank (the issuer). As Visa’s guide to how 3D Secure works describes, the merchant sends transaction details through the network to your bank, which assesses the risk using data such as device type, location and spending patterns. Then one of two things happens:

    • Frictionless flow: the bank judges the payment low-risk and approves the authentication in the background. You see nothing.
    • Challenge flow: the bank wants more proof and asks you to verify, usually with a one-time code, approval in your banking app or biometrics.

    Why your bank asks more often sometimes

    Challenges are more likely when a payment looks different from your usual pattern: a new merchant, a larger amount, a foreign currency, a new device or browser, or a different country from your normal one. A run of challenges doesn’t mean something is wrong with your card. It means your bank is being careful.

    Why 3D Secure fails

    CauseWhat you seeFix
    Code sent to an old phone numberNo text arrivesUpdate your mobile number with the bank, then retry
    Banking app not set up for approvalsPrompt says to approve in app, nothing appearsOpen the app, sign in, enable notifications or approvals
    Code typed wrong or expired“Authentication failed” after entering the codeRequest a new code and enter it promptly
    Too many failed attemptsVerification is blocked or every try failsWait, then contact your bank to reset
    Pop-up blocked or extension interferingBlank or frozen verification windowDisable blockers for the site or try another browser
    Session timed outBox closes before you finishHave your phone ready and restart checkout
    Bank or network outageErrors at several merchants at onceWait and retry later
    Bank declined the payment on risk groundsVerification passes but payment is declinedCall the bank to confirm it was you
    Card doesn’t support 3D SecureMerchant rejects the card at verificationAsk your issuer, or use another card

    Step-by-step: what to do when 3D Secure fails

    1. Check the basics. Re-enter the card number, expiry, security code and billing address exactly as your bank has them.
    2. Get your phone ready first. Have it in hand, open your banking app and make sure you have signal before you press pay.
    3. Turn off pop-up and ad blockers for the checkout. The verification window often runs in a frame that blockers interrupt. A private window without extensions is a quick test.
    4. Request a fresh code once. Use only the most recent code. Older codes usually stop working when a new one is sent.
    5. Stop after two or three tries. Repeated failures can lock verification for that card. Retrying ten times makes things worse.
    6. Check your bank’s app for messages. Many banks show a pending approval or a fraud alert there, even when a text doesn’t arrive.
    7. Call your bank. Ask whether the attempt was blocked, whether your phone number is current and whether your card is enrolled for online authentication.
    8. Try another payment method if it’s urgent. A wallet such as Apple Pay or Google Pay, or a different card, can get you through while the bank fixes the issue.

    What not to do

    • Never share a code with anyone who contacts you. A real bank will not ask you to read out a verification code. Codes you didn’t request mean someone may have your card details.
    • Don’t look for cards that skip verification. Avoiding 3D Secure removes a fraud protection and often breaks the merchant’s rules. Fix the authentication instead.
    • Don’t keep retrying across several cards in a row. Rapid attempts look like fraud to merchants and can get your account flagged.

    Is 3D Secure worth the hassle?

    For shoppers, yes. It makes stolen card details much harder to use online, and most payments pass without any visible step. Its limits are worth knowing, though. It confirms that you are the cardholder; it does not check whether a shop is honest. If you approve a payment to a scam site, 3D Secure has done exactly what it was designed to do. And it isn’t applied to every transaction, so it is one layer of protection among several.

    3D Secure and prepaid virtual cards

    Prepaid and virtual cards also go through 3D Secure when the issuer supports it, which many merchants now expect for online payments. When you choose a prepaid card, check that the provider supports 3D Secure, especially for subscriptions and software.

    Vizovcc, for example, says every card it sells supports 3D Secure. Its prepaid virtual cards are bought with crypto from an account balance, and each card’s details appear in your dashboard once it is ready. If a payment fails, the cause is often simpler than 3DS: the balance doesn’t cover the charge plus tax, or the card is frozen. The dashboard lets you freeze and unfreeze cards, so it is worth checking that first. Vizovcc’s decline checklist for subscription cards walks through those checks: confirm the balance, confirm the card isn’t frozen, re-enter details carefully and wait before retrying.

    Two honest points. Even with 3D Secure, any merchant can decline a prepaid card, so no provider can promise acceptance. And Vizovcc card purchases are final, so read the card page for currency and balance before buying. If verification keeps failing on a Vizovcc card, contact its support through live chat, WhatsApp, Telegram or email rather than retrying repeatedly.

    Frequently asked questions

    Why didn’t I get my 3D Secure code?

    The most common reasons are an outdated phone number on your bank account, weak signal, or a bank that now uses app approvals instead of texts. Check your banking app, then call the bank.

    Is “3D Secure failed” the same as a declined card?

    No. A 3D Secure failure means the identity check didn’t complete. A decline means the bank refused the payment itself. You can pass 3D Secure and still be declined, for example for insufficient funds.

    Can I turn 3D Secure off?

    Generally no. Whether a check is required is decided by the merchant, the network and your bank, not by the shopper.

    Does 3D Secure cost anything?

    Not for shoppers. There is nothing to download or sign up for beyond your bank’s normal app or text verification.

    Key takeaways

    • 3D Secure confirms you are the cardholder; most payments pass in the background.
    • Failures usually come from outdated phone numbers, app settings, blockers, timeouts or too many attempts.
    • Stop after a few tries and call your bank instead of retrying repeatedly.
    • Never share verification codes, and never look for ways around the check.
    • Prepaid virtual cards that support 3D Secure, such as Vizovcc’s, still need enough balance and an unfrozen card.

    Before your next big online payment, check that your bank has your current phone number and that app approvals are switched on. If you are looking for a prepaid card that supports 3D Secure for subscriptions, take a look at Vizovcc and read each card page before you buy.

  • Expense Cards for Contractors: A Card That Ends With the Job

    Expense Cards for Contractors: A Card That Ends With the Job

    Here is an example many small agencies will recognize. You bring in a freelance video editor for an eight-week project. In week one they need stock footage, a music license and a month of a cloud storage plan. You have two easy choices: let them pay and add the costs to their invoice, or send them the company card number. The first means waiting on receipts and checking markups. The second means that, eight weeks later, a person who no longer works with you still has a working company card number saved in their browser.

    Contractors and temporary staff need to spend money on your behalf, but they sit outside most of the systems that manage employee spending. This guide covers the options for a contractor expense card, how to set one up so it stays tied to the contract, and how to retire it cleanly when the work is done.

    Why contractors need a different approach

    • Short tenure. A contract may last weeks. Whatever access you grant has to be undone soon, and often by someone other than the person who granted it.
    • Outside HR systems. Contractors usually aren’t in the HR platform, so the automatic offboarding steps that cover employees don’t run for them.
    • Several clients at once. A freelancer may be juggling work for many companies. Your card number is one of many saved payment methods on their devices.
    • Classification sensitivity. How much control you take over a worker’s job, including their expenses, is one of the factors tax authorities look at when deciding whether someone is a contractor or an employee.

    Five ways to cover contractor expenses

    OptionUpfront cost to contractorCompany visibilityClean-up at contract end
    Contractor pays and bills the cost on their invoiceFull amount until you pay the invoiceLow: one invoice line per monthNone, but subscriptions may stay in their name
    Reimbursement against receiptsFull amount until reimbursedMedium: receipts arrive lateMove any subscriptions off their personal card
    Shared company cardNoneLow: mixed with everyone’s chargesReplace the card everywhere it is saved
    Company buys on requestNoneHighNone, but slow for urgent purchases
    Dedicated card per contractorNoneHigh: every charge on the card is theirsRetire one card

    For contractors who make more than a handful of purchases, a dedicated card is usually the cleanest choice. Every charge on it belongs to one person and one contract, and ending it doesn’t affect anyone else.

    Don’t rely on the expiry date

    A common idea is to give a contractor a card that expires when the contract ends. Some corporate card programs let you set a custom expiry, but many cards, including most prepaid cards, carry a fixed expiry measured in years. Contracts also change: they get extended, paused or ended early. An expiry date set at kickoff is often wrong by the end.

    A more reliable approach is to treat the card as part of the contract and retire it as a step in the contract’s closing checklist. That works with any card, whatever its expiry.

    Setting up a contractor expense card, step by step

    1. Write allowable expenses into the contract. List what the company pays for directly (software, licenses, materials, travel) and what the contractor covers from their fee.
    2. Set the project expense budget. Agree an amount for the whole contract or per month, and who approves anything above it.
    3. Issue one card for this contractor only. Never reuse a card from a previous contractor, and never share one between two people.
    4. Use company accounts where possible. If the contractor needs a tool, create it under a company email and add them as a user. Save the card to the company account yourself, so the contractor uses the tool without handling the card number.
    5. Share card details securely when you must. Use a business password manager with access for that one person, not chat or email.
    6. Record the card in a register. Last four digits, contractor name, contract reference, start date, planned end date and budget. Keep full numbers and CVVs out of it.
    7. Review charges every two weeks. Short contracts leave little time to catch problems at month end.

    The contract-end checklist

    1. Remove the card from every site and tool where it is saved.
    2. Cancel subscriptions the project no longer needs, or move them to a long-term company card.
    3. Remove the contractor’s user access from company tools and ad accounts.
    4. Collect any missing receipts and reconcile the card against the project budget.
    5. Mark the card as retired in the register, with the date.
    6. If the card details were ever shared with the contractor and a subscription has to keep running, buy a new card for it rather than leaving the old number in use.

    Which option fits the contract?

    • One or two small purchases in total: let the contractor bill them as pass-through costs on the invoice.
    • Regular purchases over several weeks: issue a dedicated card and close it with the contract.
    • Large or one-off purchases, such as equipment: buy them directly in the company’s name.
    • Long-running contract that behaves like a role: review whether the arrangement is still a contract at all.

    A note on worker classification

    Paying for a contractor’s work expenses is normal, but it isn’t neutral. In the US, the IRS guidance on contractors versus employees lists financial control, including whether expenses are reimbursed and who provides tools and supplies, as one of the categories it considers. A company card for project costs doesn’t decide the question on its own, but it is one factor among many. Keep the card scoped to project costs agreed in the contract, and ask your advisor if you are unsure. Other countries apply their own tests.

    Example: one prepaid card per contractor with ZenVCC

    ZenVCC is a prepaid virtual card platform that suits the dedicated-card model. You fund one company balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), each deposit is checked on its blockchain before it is credited, and you buy a separate prepaid Visa, Mastercard or American Express card for each contractor or project.

    How it maps to the steps above:

    • A fixed ceiling. A prepaid card can’t pay more than its balance, so the contractor can’t overspend the card.
    • Low cost per card. Each card has a one-time $10 issue fee on top of its price, $0.10 per payment and no monthly fee, so a card for an eight-week contract doesn’t leave a recurring cost behind.
    • Retire by process, not by expiry. Cards are valid for three years from the day they are ready, so the expiry won’t match a contract end date. Close each card with the checklist above.

    Know the limits too. ZenVCC has no freeze button or per-card spending limit, and there are no team roles or sub-accounts: whoever signs in sees every card. Contractors should never get the login. Keep it with one person in the company, who adds cards to company tool accounts or shares a single card’s details through a password manager. If a contractor’s card details ever end up in the wrong place, ZenVCC’s advice on what to do when card details leak is to remove the card from every site where it is saved and buy a new card for those payments, which matches the contract-end checklist.

    Mistakes to avoid

    • Passing a card from one contractor to the next. Charges from two people on one card can’t be cleanly separated.
    • Letting contractors open tools in their own name. When they leave, you lose the account, the data and the cancel button.
    • Skipping the closing checklist because the card “expires anyway.” Most cards outlive the contract by years.
    • Paying for things outside the contract. Personal or non-project costs blur both your books and the working relationship.

    Key takeaways

    • Contractors need spending access, but they fall outside the systems that clean up employee access.
    • A dedicated card per contractor keeps every charge attributable and makes the exit simple.
    • Don’t count on the card’s expiry date. Retire the card as part of the contract’s closing checklist.
    • Keep tools in company accounts and card numbers away from contractors where you can.
    • Scope the card to project costs written into the contract.

    Before your next contractor starts, add two lines to the contract template: allowable expenses and the card’s retirement step. If you want a prepaid card per contractor with no monthly fee, take a look at ZenVCC and see whether it fits how you run contracts.

  • Shadow IT Is a Finance Problem: Find Every Software Charge

    Shadow IT Is a Finance Problem: Find Every Software Charge

    Consider an example that plays out in many mid-sized companies. During an annual security review, IT finds three different file-sharing tools holding customer documents. None of them went through procurement. One was expensed by a sales manager who left last spring, and it renewed last month for a full year on a card that still works. Nobody in IT knew it existed. Finance had the charge all along, coded as “Software, misc.”

    Shadow IT, meaning software and cloud services used without IT’s knowledge or approval, is usually treated as a security issue. It is one. But nearly every unapproved tool has to be paid for, which means it leaves a trail in finance data before it shows up anywhere else. This guide explains where shadow IT spend hides, how finance and IT can find it together, and how routing software purchases through known cards keeps it from coming back.

    Why shadow IT starts in the books

    Most SaaS tools are sold with a credit card and a sign-up form. A team lead with a deadline and a budget doesn’t need IT to start a trial, and once the trial converts, the tool becomes part of how the team works. The purchase decision happens at the card, so the card data is where you can see it.

    That makes finance the natural partner for discovery. IT knows which tools are approved and what risk they carry. Finance knows what is being paid for. Neither list is complete without the other.

    Where shadow IT spend hides

    • Expense reports. A software subscription paid on a personal card and reimbursed as “office supplies” or “misc.”
    • Shared company cards. One card used by a whole department, with charges coded by whoever does the books that month.
    • Free trials that convert. A trial started with a card turns into a paid plan, often annual, without a second decision.
    • In-app upgrades and add-ons. An approved tool picks up paid seats, storage or AI features added by users with billing rights.
    • Cloud marketplaces. Third-party software billed through a cloud provider’s invoice, where it looks like infrastructure spend.
    • Departmental budgets. Marketing, sales and engineering often buy their own tools from their own budget lines.

    Discovery methods compared

    No single source finds everything. The useful question is what each one misses.

    MethodWhat it findsWhat it missesWho runs it
    Card and expense data reviewAnything paid for, including tools IT has never seenFree tools and tools paid by another companyFinance
    Single sign-on (SSO) logsApps connected to company identityAnything signed up with a password or personal emailIT
    Network or browser monitoringWeb apps people visit on managed devicesPersonal devices, and whether the app is paidIT or security
    Vendor invoices in accounts payableTools on formal contractsCard and expense purchases, which is where most shadow IT sitsFinance
    Team surveysTools people remember and are willing to mentionAnything forgotten or deliberately left outIT with managers

    Card and expense data is the cheapest place to start, because finance already has it. Security frameworks treat this as basic hygiene: CIS Control 2 calls for an active inventory of all software so that unauthorized software can be found and dealt with.

    A step-by-step plan to find and stop shadow IT spend

    1. Pull 12 months of card and expense data. Include company cards, reimbursed expenses and accounts payable. Filter for software, SaaS, cloud and app-store merchants, plus anything coded to vague accounts.
    2. Build the inventory. One row per tool: vendor, monthly or annual cost, renewal date, payment method, who pays and who uses it.
    3. Find an owner for every tool. If nobody claims it, that is useful information too. Unclaimed tools go to the top of the review list.
    4. Review with IT. For each tool, decide: approve, consolidate into an existing tool, or cancel. Check what data each tool holds before cancelling.
    5. Create a simple request path. A short form or ticket for new software, with a promised response time. People bypass IT when approval is slow, not because they enjoy it.
    6. Move approved tools onto known cards. Pay each approved vendor from a card the company controls, ideally one card per vendor, under a company billing email.
    7. Close the expense-report route. Make software reimbursement an exception that needs IT sign-off. When the approved path is faster, this rule rarely has to be enforced.
    8. Review new merchants monthly. Any software merchant that appears on a card or expense report without an inventory row is a new shadow IT candidate.

    What card controls can and can’t do

    Many corporate card programs offer controls such as per-card spending limits, merchant category restrictions and approval workflows. These help, but the bigger gain comes from structure: when every approved tool has its own card, the card becomes the tool’s ID. A software charge on any other card, or on an expense report, stands out immediately.

    Controls also have limits. They can’t tell you whether a tool is safe, whether its data is backed up or whether a cheaper approved tool already does the job. That is IT’s review. Cards give finance the visibility; the decision still needs both teams.

    A quick triage guide for each tool you find

    • Holds customer or employee data and has no owner: secure the data, export it, then cancel.
    • Duplicates an approved tool: move the users across and cancel at renewal.
    • Used by several people and does something no approved tool does: run it through the request path and approve it properly.
    • Used by one person, low cost, no sensitive data: approve or cancel quickly. Don’t spend more time reviewing it than it costs.

    Example: one card per approved vendor with ZenVCC

    ZenVCC is a prepaid virtual card platform that fits step 6 of the plan. A company funds one balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), each deposit is checked on its blockchain before it is credited, and you buy a separate prepaid Visa, Mastercard or American Express card for each approved vendor. Its service page recommends exactly this pattern: a separate card per vendor, so every charge on a card belongs to one vendor, and when you stop using a service, you stop using its card.

    What it adds to a shadow IT program:

    • No monthly fee. Each card has a one-time $10 issue fee on top of its price and costs $0.10 per payment, with $0 a month, so a card for each small approved tool doesn’t add recurring overhead.
    • A hard ceiling. A prepaid card can’t pay more than its balance, so a surprise upgrade can’t run up an open-ended bill.
    • Three-year validity. Cards are valid for three years from the day they are ready, which keeps renewals from failing on expired cards.
    • Refund if a card can’t be prepared. The full amount, issue fee included, returns to the balance.

    Be clear about what it doesn’t do. ZenVCC doesn’t offer merchant locks or per-card spending limits, so “one card per vendor” is a rule your team keeps, not one the card enforces. It has no team roles or sub-accounts either: whoever signs in sees every card, so the login should sit with the one person who owns software payments. Vendors also decide which cards they accept, and the provider’s own page notes that several major cloud and workspace providers refuse prepaid or virtual cards, so check each vendor’s billing rules first. For the vendors that do accept them, separate cards for SaaS and cloud vendors make the monthly new-merchant review in step 8 fast.

    Mistakes to avoid

    • Treating discovery as a one-time audit. New tools appear every month. Make the merchant review a standing task.
    • Cancelling before checking data. A tool nobody approved may still hold the only copy of important files.
    • Punishing people who used shadow tools. They were solving a real problem. Fix the request path so they don’t need to again.
    • Leaving billing on personal emails. When the buyer leaves, so does access to the invoices and the cancel button.

    Key takeaways

    • Almost every shadow IT tool is paid for, so finance data is the fastest place to find it.
    • Combine card and expense reviews with SSO logs and IT knowledge; each source misses something.
    • Give every approved tool an owner, a company billing email and its own card.
    • A faster request path does more to stop shadow IT than a stricter rule.
    • Review new software merchants every month, not once a year.

    Start this month with a single export: 12 months of card and expense lines filtered for software merchants. Share it with IT and see how many tools are new to both of you. If you want a prepaid way to give each approved vendor its own card with no monthly fee, take a look at ZenVCC.

  • Canceled but Still Charged? Your Rights and How to Stop It

    Canceled but Still Charged? Your Rights and How to Stop It

    Take this example. In January you cancel a streaming plan, see a “sorry to see you go” screen and forget about it. In March, the same $15.49 charge appears on your card. Then it appears again in April. You are sure you canceled, but you never saved the confirmation, and the company’s help page sends you in circles.

    Being charged after you cancel is one of the most common billing complaints, and it is fixable. The order matters, though. Start with your rights, because they are what get your money back. Then fix the cause, and only then add the safeguards that make it hard for this to happen again.

    Your rights come first

    The rules below describe the United States. If you live elsewhere, your national consumer agency publishes the equivalent rights, and they are often just as strong.

    If you paid by credit card

    Under the Fair Credit Billing Act, you can dispute billing errors with your card issuer, including charges for things you did not accept or that were not delivered as agreed. Timing is strict: as the FTC’s guide to disputing credit card charges explains, your letter must reach the issuer within 60 days after the first bill with the error was sent to you. Write to the billing-inquiry address, not the payment address. The issuer must acknowledge your dispute within 30 days and resolve it within 90.

    If you paid by debit card or bank transfer

    You can withdraw a company’s permission to take automatic payments. According to the CFPB’s steps for stopping automatic payments, you tell the company and then your bank that you have revoked authorization, and follow up both in writing. Payments the company takes after that are errors you can ask your bank to refund. Your bank may also offer a stop payment order, usually for a fee.

    Chargebacks through the card network

    When you dispute a charge, your issuer can raise a chargeback with the merchant through the card network. Networks have dispute categories that cover recurring charges after a cancellation. Your evidence, especially the cancellation date and any confirmation, decides how that goes.

    Rules on automatic renewals

    The federal Restore Online Shoppers’ Confidence Act requires online sellers of recurring plans to provide a simple way to stop the charges. The FTC’s broader “click-to-cancel” rule was struck down by a federal appeals court in July 2025 before it took effect, but many states have their own automatic renewal laws that still apply.

    Why charges continue after you cancel

    Before you dispute anything, find the likely cause. It shapes what you say to the merchant and to your bank.

    • The cancellation never completed. Many flows have a retention offer or a final “confirm” button. Closing the page early leaves the plan active.
    • You canceled in the wrong place. A plan bought through an app store must be canceled there. Deleting the app does nothing.
    • It was a different account. A second login, an old email address or a family member’s plan can all bill the same card.
    • The charge covers an earlier period. Some services bill in arrears or charge a final usage invoice after cancellation.
    • An annual plan renewed. You canceled a monthly add-on but not the yearly base plan.
    • Your new card was updated automatically. Many issuers take part in network card-updater services that pass a replacement card’s details to merchants that held the old one. Replacing a card does not cancel a subscription.
    • It is a pending authorization. A temporary hold may drop off without becoming a charge.
    • It is a billing error. Sometimes the merchant simply got it wrong.

    What to do, step by step

    1. Collect your evidence. Find the cancellation email, a screenshot or the date you canceled. Check your inbox and the account’s billing history.
    2. Identify the charge. Confirm it is posted, not pending, and work out which period it covers and which account it came from.
    3. Contact the merchant in writing. Give the cancellation date, ask for the plan to be closed and request a refund of every charge after that date. Keep a copy.
    4. Dispute with your card issuer if the merchant does not fix it. For credit cards, write within the 60-day window. For debit cards, report it to your bank promptly and keep the dates.
    5. Revoke authorization to stop future charges. Tell the merchant and your bank in writing that the merchant may no longer charge you. Ask about a stop payment order or a merchant block.
    6. Check for card-updater carryover. If you replaced the card, ask your issuer whether the new number was shared with that merchant.
    7. Report patterns. If a company keeps charging people after cancellation, you can report it to the FTC or your state attorney general.

    Which tool solves which problem

    ActionCan get money backStops future chargesLimits
    Cancel with the merchantOnly if the merchant agreesYes, when completedYou need proof if it fails
    Dispute or chargeback with your issuerYes, if the dispute succeedsNo, on its ownDeadlines apply, and evidence decides the outcome
    Revoke authorization with your bankLater charges count as errorsYesDebit card charges can be harder for banks to block
    Stop payment order or merchant blockNoUsuallyFees may apply, and coverage varies
    Replace the card numberNoNot always, because of card updatersEvery other service on that card needs updating
    Separate prepaid card for the subscriptionNoLimits how much can be taken to the funds on the cardDispute options depend on the card provider

    Preventing it next time

    • Save every cancellation confirmation. Make a folder in your inbox for them. It is the single most useful piece of evidence in a dispute.
    • Cancel where you subscribed. App store plans in the app store, website plans on the website.
    • Set a reminder before trial and renewal dates. Trial terms still apply, so cancel a few days early.
    • Keep subscriptions off your main bank card. If a merchant keeps billing, you want the damage to stay away from the account that pays your rent.
    • Give each subscription its own card. A statement with one merchant on it makes a stray charge obvious.

    A backstop, not a replacement: prepaid cards per subscription

    The last two habits are where a prepaid card can help. If a subscription sits on a prepaid card that holds only what you intend to spend there, a merchant that keeps charging after you cancel can only take what is left on that card. Your bank account is not on file with the merchant at all.

    ZenVCC is one provider of this kind of card, and it is worth being exact about what it does and does not do. ZenVCC does not offer a way to freeze or close a card from its dashboard, so it cannot switch a card off the way some bank apps can. Its FAQ also does not describe a dispute process for card charges, so ask its support before you count on one. Your rights against the merchant, and the steps above, still come first.

    What it does offer is a separate prepaid virtual card for each subscription, bought from one balance funded with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL). Each card has a one-time $10 issue fee, each payment costs $0.10 and there is no monthly fee. Cards are valid for three years. A few terms matter for this use:

    • Size each card carefully. Card purchases are final once the details are ready, and there are no transfers from a card back to your balance.
    • Cards cannot be topped up from the dashboard. A card can only spend the funds it holds.
    • Track charges at the merchant. The dashboard does not list card payments, so use each service’s billing page and save its receipts.
    • Remove the card when you leave. Deleting it from the merchant account, after canceling, adds one more barrier.

    For the full details on balances and refunds, read ZenVCC’s FAQ on balances, refunds and card details.

    Key takeaways

    • Start with your rights: credit card billing disputes have a 60-day written window, and debit payments can be stopped by revoking authorization with the merchant and your bank.
    • Find the cause first. Incomplete cancellations, app store plans and card updaters explain many surprise charges.
    • Replacing your card does not cancel a subscription and may not stop the charges.
    • Save every cancellation confirmation, because it decides most disputes.
    • A prepaid card per subscription limits how much a merchant can take, but it is a backstop, not a substitute for canceling and disputing.

    If you are dealing with a charge right now, start with step 1 today and keep every message in writing. For future subscriptions, consider keeping them on cards that hold only what you plan to spend. ZenVCC is one prepaid option to compare against your bank’s tools.

  • How Netflix, Spotify and YouTube Premium Bill Your Card (and Why Renewals Fail)

    How Netflix, Spotify and YouTube Premium Bill Your Card (and Why Renewals Fail)

    Your card worked when you signed up, and it worked last month. Then this morning you see “Your payment was declined” and a banner asking you to update your payment details. Streaming renewals fail for a handful of mechanical reasons, and once you know how these services bill, most of them take minutes to fix.

    Quick answer

    1. Check the basics the service compares: expiry date, security code and billing postal code.

    2. Make sure the card is enabled for online, recurring and (if needed) international payments.

    3. Make sure the balance covers the charge on the billing date, especially on a prepaid or debit card.

    4. If you pay through an app store, carrier or bundle, fix it there, not on the service’s site.

    How streaming billing works

    Every major streaming service uses the same basic model.

    At signup, you enter a card, and the service checks it. That may be a $0 verification or a small authorization that’s later released, and in many regions the issuer may ask for a 3D Secure confirmation. You also agree that the service can store the card and charge it on a schedule.

    On each billing date, the service charges the stored card as a merchant-initiated transaction. You don’t take part, and there’s usually no 3D Secure step, because your consent at signup covers it. The charge is normally in the currency of the country your account is registered in.

    If you pay through a partner (an app store, a mobile carrier, a TV or internet bundle), the partner bills you and the streaming service only sees whether the partner says you’ve paid. A declined card in that setup is a problem with the partner’s billing, not the streaming service’s.

    That’s why a card can pass at signup and fail later: the renewal is a different kind of transaction, on a different day, and your issuer, your balance or your card settings may have changed in between.

    What each service says about cards and failed payments

    The three services publish their own rules. Here’s what their help pages say, as checked on 25 Oct 2026:

    NetflixSpotifyYouTube Premium
    When you’re billedMonthly, on the date you signed upMonthly, on your plan’s renewal dateMonthly, on your membership’s billing date
    Card requirements statedVisa, Mastercard and Amex cards “must be enabled for recurring e-commerce transactions”; prepaid cards with those logos are accepted; virtual cards are accepted “in select markets”; you may need to enable international transactionsCard must be enabled for “foreign, secure online, and recurring purchases”Expired cards and incorrect billing addresses are named as common causes of failure
    If a renewal failsFix the details and retry the charge from your accountYou don’t lose Premium right away; Spotify tries again “over the next few days”You get an email and 3 days to fix it while payment is retried; then the membership shows as “Paused” for 30 days
    Where to fix itAccount page, or your partner if billed through oneAccount page, under your planyoutube.com/paid_memberships or Purchases and memberships in the app

    If Spotify’s retries keep failing, the account loses Premium and moves to the free tier [VERIFY: Spotify’s official wording on what happens after retries fail]. Netflix’s help pages don’t publish a retry schedule, so don’t count on one.

    The six reasons renewals fail

    1.  Not enough balance on the billing date. On a debit or prepaid card, the charge is declined as insufficient funds (decline code 51) if the money isn’t there when the service tries. The service’s clock decides the time, so “the 15th” may mean late on the 14th where you live.

    2.  An expired or replaced card. A new expiry date or card number means the stored details are out of date (an expired card is code 54). Some banks pass new details to merchants automatically; many don’t.

    3.  Card settings. Many banking apps let you switch off online, recurring or international payments. Netflix and Spotify both say the card must allow these. If your bank blocks recurring payments by default, the renewal fails even with money in the account.

    4.  A billing details mismatch. Netflix asks you to check the expiry date, security code and billing postal code. If the postal code doesn’t match what your issuer holds, an address check can fail.

    5.  Card type or country. Some cards aren’t accepted in some markets. Netflix, for example, accepts prepaid cards with the right logos, but virtual cards only in select markets. A card issued in another country may also trigger your issuer’s cross-border rules.

    6.  A generic issuer decline. “Do not honor” (code 05) means the issuer refused without saying why, often because its fraud model flagged the charge. Only the issuer can tell you more.

    A note on country: each service decides your account’s country from its own signals, and that sets the price, catalog and accepted payment methods. Your card can’t change it. Using a VPN or switching regions to get a cheaper price breaks these services’ terms and can get the account closed.

    Fixing a failed renewal: step by step

    1.  Read the exact message in your account or email. “Update your payment method” and “your bank declined” point to different fixes.

    2.  Check whether you’re billed through a partner. If so, go to that partner’s billing settings.

    3.  Compare the stored details with your card: number, expiry date, security code and billing postal code. Correct anything that differs.

    4.  Open your banking or card app. Make sure online, recurring and international payments are allowed, and that the card isn’t frozen or locked.

    5.  Check the balance covers the plan price, plus any tax.

    6.  Retry the payment from your account page, or wait for the service’s next automatic attempt.

    7.  If the issuer still declines, call it and ask why. If the card type isn’t accepted, switch to a different payment method.

    Using a prepaid virtual card for streaming

    Prepaid virtual cards suit streaming well when they’re accepted: you can put each service on its own card, cap what it can charge, and freeze it when you’re done. Check the service’s payment page for your country first, because acceptance varies.

    As one example, VCCBuy’s Netflix card guide covers using its prepaid virtual Visa or Mastercard for that service. You fund the card with USDT on TRC20, BEP20, ERC20, Polygon or Solana, or with USDC, ETH and several other coins (no BTC). The Visa Classic has a $9.99 issue fee, a 3% top-up fee and no monthly fee. If the service asks for 3D Secure at signup, the code appears in the dashboard for 10 minutes, with no phone number needed. You can also save a billing name and postal address on each card, which helps the address check, and freeze the card if you cancel.

    The limits matter here too. VCCBuy is not a bank, the cards are online only, deposits are checked before they are credited, and some services or markets decline prepaid or virtual cards. A VCCBuy card renews only if its balance covers the charge on the billing date, and the service’s own country and card rules always apply.

    Renewal checklist

    ☐  I know my billing date for each service, and I’ve noted it in my calendar

    ☐  Each card allows online, recurring and (if needed) international payments

    ☐  The billing postal code saved at each service matches my card

    ☐  Prepaid or debit balances cover each charge a few days early

    ☐  I’ve updated expiry dates after any card replacement

    ☐  I know which subscriptions are billed through an app store, carrier or bundle

    ☐  My account country is the country I actually live in

    FAQ

    Why did my card work at signup but fail at renewal? Signup was often a $0 or small verification and may have included your confirmation through 3D Secure. The renewal is a full-price, merchant-initiated charge on a later date. A low balance, a changed card setting, an expired card or an issuer fraud flag can each block it.

    How long do I have before I lose access? It depends on the service. YouTube Premium gives you 3 days while it retries, then pauses the membership for 30 days. Spotify retries over a few days before you lose Premium. Netflix doesn’t publish a timeline, so fix the payment as soon as you see the notice.

    Can I pay for Netflix with a prepaid or virtual card? Netflix says it accepts prepaid cards that carry the Visa, Mastercard or Amex logo, and virtual cards in select markets. If your virtual card is declined, Netflix suggests choosing a different payment method.

    Conclusion

    Streaming services bill a stored card on a schedule, and renewals fail when something about that card has changed since signup: its balance, its settings, its details or the issuer’s view of it. Check those in order and most declines take minutes to clear. Before your next billing date, run through the checklist and set a reminder to make sure each card is ready.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about recurring billing and why renewals fail, using each service’s own published rules.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • SAP CPI Integration Architecture: Components and Data Flow

    SAP CPI Integration Architecture: Components and Data Flow

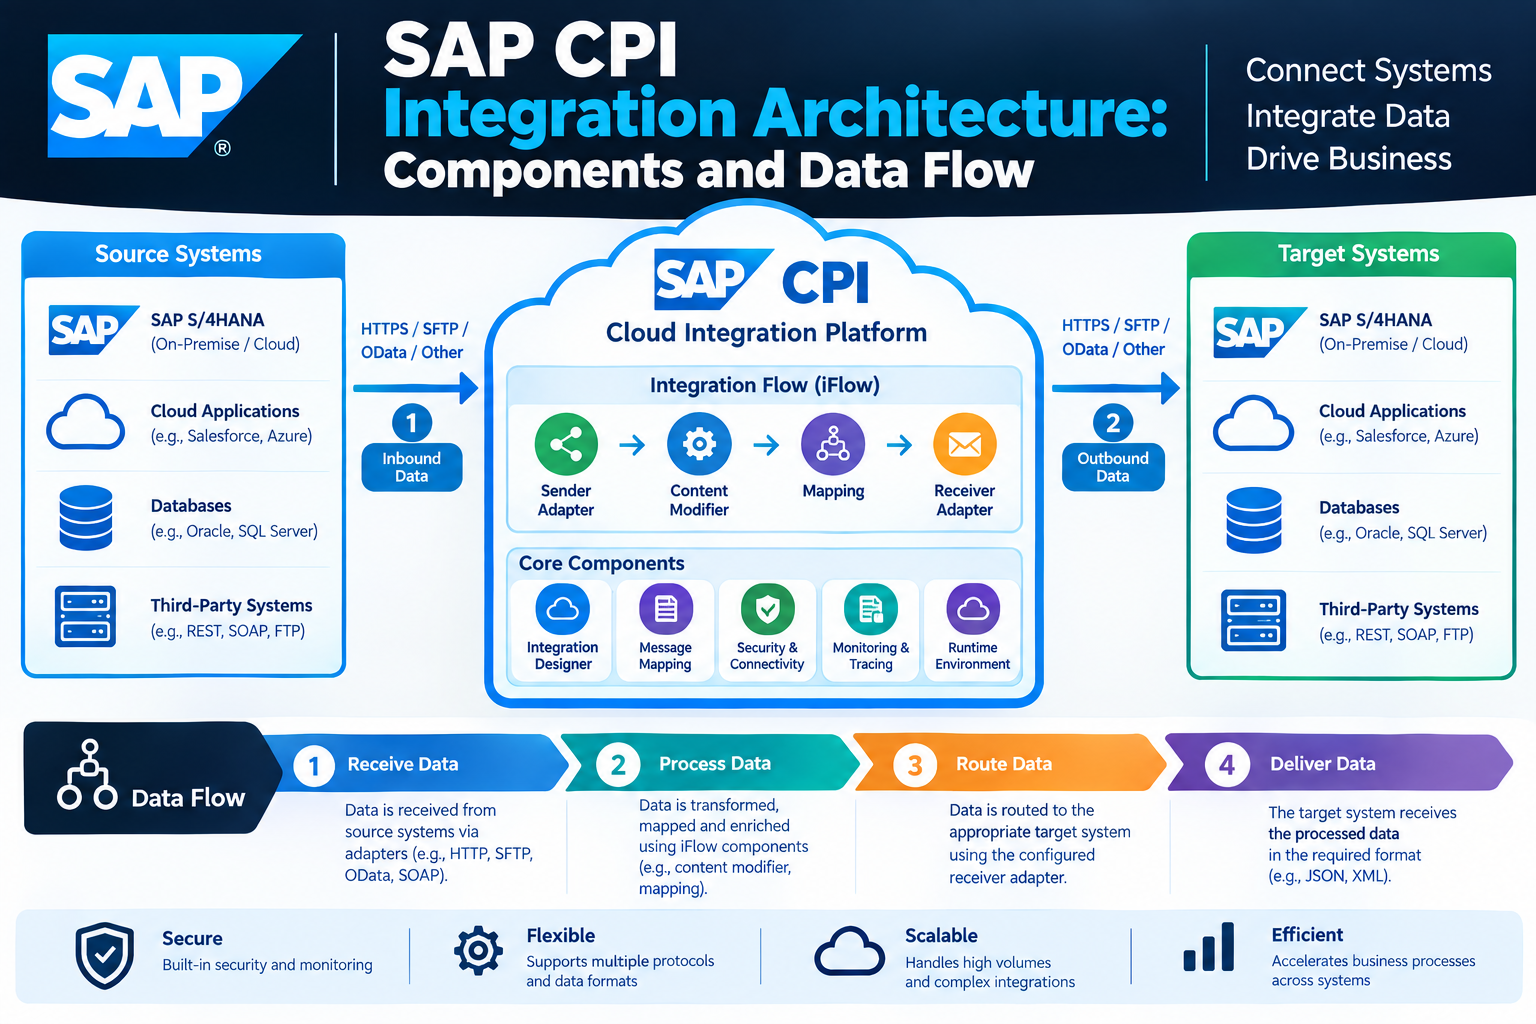
    SAP CPI Integration provides a structured way to connect SAP applications, non-SAP applications, cloud platforms, and on-premise systems. It manages how business data moves between different systems and defines how messages are received, processed, transformed, routed, and delivered. SAP currently provides Cloud Integration as a capability within SAP Integration Suite on SAP Business Technology Platform (SAP BTP). It supports application-to-application (A2A), business-to-business (B2B), and business-to-government (B2G) integration scenarios across cloud, on-premise, and hybrid environments.

    The architecture of SAP CPI Integration is based on integration flows, also known as iFlows. An integration flow defines the sender, receiver, communication adapters, processing steps, and message flow required for an integration scenario. This architecture allows organizations to control data movement without requiring every application to communicate directly with every other application.

    What Is SAP CPI Integration Architecture?

    SAP CPI Integration architecture describes the components and processing stages used to transfer data between connected systems. The architecture normally begins with a source or sender system, passes the message through an integration flow, processes the data according to defined rules, and sends the result to one or more receiver systems.

    An integration flow acts as the central processing model. SAP documentation explains that an integration flow specifies how a message is processed on the tenant. Developers can define senders and receivers, communication adapters, and message-processing steps within the graphical integration flow editor.

    For example, an organization may receive a sales order from an e-commerce platform. SAP CPI Integration can receive the order, validate its content, transform the data into an SAP-compatible structure, enrich the message with additional information, and send it to SAP S/4HANA.

    Main Components of SAP CPI Integration Architecture

    The architecture contains several important components that work together. Each component has a specific role in the movement and processing of business data.

    Integration Package

    An integration package provides a logical container for integration artifacts. It can contain integration flows and other artifacts used within an integration project. SAP documentation describes packages as a way to organize artifacts such as integration flows, value mappings, and APIs.

    For example, a company could create a package called Global_Sales_Integration and place multiple sales-related integration flows inside it. This organization makes integration content easier to manage and maintain.

    Integration Flow or iFlow

    The integration flow is the central design component of SAP CPI Integration. It describes how a message travels through the integration runtime.

    An iFlow can contain sender and receiver participants, adapters, processing steps, mapping, routing, filtering, scripts, and other integration components. Message flows connect the different elements and determine the processing sequence.

    A simple architecture can be represented conceptually as:

    Sender System → Sender Adapter → Integration Process → Processing Steps → Receiver Adapter → Receiver System

    This model can become more complex when the integration requires multiple receivers, conditional routing, enrichment, asynchronous processing, or error handling.

    Sender

    The sender is the system or application that starts or provides the message. It can represent an SAP application, cloud application, partner system, web application, or another connected source.

    For example, SAP S/4HANA could send an IDoc containing customer information, while an external application could send an HTTP request containing an order.

    Receiver

    The receiver is the system that receives the processed message. A receiver can be an SAP application, third-party application, database, SFTP server, web service, or another supported endpoint.

    A single integration scenario can contain different sender and receiver combinations depending on the business process.

    Adapters

    Adapters provide the technical connection between external systems and the Cloud Integration runtime. SAP documentation describes adapters as the mechanism used to specify the technical protocols for connecting senders and receivers to the integration flow.

    The appropriate adapter depends on the communication technology used by the connected system. Common technologies include HTTP, HTTPS, SOAP, SFTP, OData, IDoc, and other supported protocols.

    For example, an HTTPS sender adapter can receive a web request, while an SFTP receiver adapter can deliver a processed file to an external server.

    Message Processing in SAP CPI Integration

    After a message enters the integration flow, it can pass through multiple processing steps. These steps determine what happens to the message before it reaches the receiver.

    SAP Cloud Integration provides different processing capabilities for tasks such as transformation, routing, filtering, content modification, scripting, splitting, joining, and external service calls.

    A message may therefore follow a sequence such as:

    Receive → Validate → Transform → Enrich → Route → Deliver

    The actual sequence depends on the business requirement.

    Content Modifier

    A Content Modifier can change or add message content, headers, and properties during processing. It can be used when an integration needs to add information, modify message values, or prepare data for a later processing step.

    For example, an integration flow could add a business identifier or set a property before the message is routed to another system.

    Message Mapping

    Message mapping is used when the structure of the source message differs from the structure expected by the target system.

    For example, an e-commerce application may use:

    customer_name

    while the target SAP application expects a different field structure.

    A mapping can establish the relationship between source and target fields and apply functions where required. SAP Cloud Integration supports message mapping with supported source and target structures and provides mapping functions for transforming data.

    Router

    A Router allows the integration flow to select different processing paths based on defined conditions.

    For example, an order integration could route messages according to country:

    Germany → SAP S/4HANA Germany

    France → SAP S/4HANA France

    United Kingdom → UK Processing Flow

    This makes conditional processing possible within a single integration architecture.

    Filter

    A Filter can prevent unwanted messages or message content from continuing through a particular processing path. It is useful when only specific records or conditions should be processed.

    Script

    Scripts can provide custom processing logic when standard integration-flow steps are not sufficient. SAP documentation identifies script processing as a supported integration capability, including Java or Groovy-based scripting depending on the supported feature and scenario.

    Scripts should be used carefully because every processing step consumes tenant resources. SAP recommends designing integration flows with resource usage, resilience, and maintainability in mind.

    SAP CPI Integration Data Flow

    The data flow describes how a message moves from the source system to the target system. The message normally enters through a sender adapter and then passes through the processing steps defined in the integration flow.

    Consider an employee synchronization scenario.

    An HR application sends employee information to SAP CPI Integration through an HTTPS endpoint. The sender adapter receives the message and passes it into the integration process. A validation step checks the message, a mapping step converts the source structure into the required target structure, and a Router can determine the correct processing path. The receiver adapter then sends the transformed message to the target SAP system.

    The basic flow can be represented as:

    Source Application → Adapter → Integration Flow → Transformation → Routing → Receiver Adapter → Target Application

    This architecture separates business processing logic from the technical communication method.

    Synchronous and Asynchronous Data Flow

    SAP CPI Integration can support different processing patterns depending on the integration scenario.

    In a synchronous process, the sender expects a response during the same interaction. A request can be received, processed, sent to a receiver, and the resulting response can be returned to the sender.

    In an asynchronous process, the sender does not necessarily wait for the complete downstream processing to finish. Messaging and other integration patterns can be used when systems need to exchange information without maintaining a continuous synchronous interaction.

    The correct pattern depends on requirements such as response time, transaction behavior, system availability, message volume, and business process design.

    Security in SAP CPI Integration Architecture

    Security is an important part of the architecture because integration flows exchange business information between different systems.

    Authentication and authorization methods depend on the adapter and communication scenario. SAP Integration Suite supports different authentication options for integration-flow endpoints and connections to external systems.

    Secure communication protocols should be used when supported by the connected systems. SAP design guidance recommends encrypted protocols for secure communication with remote systems.

    Security can involve certificates, credentials, OAuth-based authentication, roles, authorization, and secure protocol configurations. The exact configuration should match the requirements of the sender and receiver systems.

    Error Handling and Monitoring

    A production integration architecture needs mechanisms for detecting and managing processing failures. An integration flow can fail because of invalid data, authentication problems, unavailable receiver systems, communication errors, mapping problems, or incorrect processing logic.

    SAP’s enterprise-grade integration guidance emphasizes resilience, graceful failure handling, supervision, resource management, and loose coupling. These characteristics help reduce the effect of failures on business processes.

    Monitoring is also important because integration teams need to determine whether messages were successfully processed. When an error occurs, developers can investigate the message-processing sequence and identify the stage where processing stopped.

    SAP CPI Integration Runtime and Deployment

    Designing an integration flow does not automatically make it active for business processing. The integration content must be deployed to the runtime environment.

    SAP explains that developers first design integration content and then deploy it. After deployment, the integration flows can operate and exchange data with connected sender and receiver systems. Cloud and on-premise systems can participate in these scenarios.

    This creates an important distinction between design time and runtime. Design time is where developers configure the integration flow. Runtime is where the deployed flow processes actual business messages.

    Naming Conventions for Integration Architecture

    Consistent naming is important when an organization manages many integration flows. SAP provides naming guidelines for integration flows, participants, channels, mappings, and other artifacts.

    For example, SAP documentation gives integration-flow naming patterns such as:

    Global_MM_PurchaseOrder

    and participant names such as:

    OP_ERP

    Channel names can use a pattern such as:

    HTTP_RCV_PurchaseOrderCreate

    Clear naming helps developers understand the purpose of an artifact without opening every configuration screen. SAP also recommends meaningful, generic names rather than technical or environment-dependent names.

    SAP CPI Integration Architecture Example

    Consider a retail company that receives orders from an online store and sends them to SAP S/4HANA.

    The online store acts as the sender. It sends an order message to an HTTPS endpoint. The sender adapter receives the request and passes it into the integration flow.

    The integration flow validates the incoming message and uses Message Mapping to convert the e-commerce structure into the format required by SAP S/4HANA. A Content Modifier can add required values, while a Router can send different orders through different processing paths.

    The receiver adapter then sends the transformed order to SAP S/4HANA. If the target system requires a response, the integration can process the response and return the required information to the original sender.

    This architecture avoids creating a direct custom connection between every application. Instead, Cloud Integration provides a controlled integration layer where connectivity, transformation, routing, security, and monitoring can be managed.

    Best Practices for SAP CPI Integration Architecture

    A well-designed architecture should keep integration flows understandable and maintainable. SAP’s enterprise-grade guidance emphasizes high availability, resilience, resource management, loose coupling, graceful failure handling, and readability.

    Keep integration flows focused on clear business responsibilities. Avoid unnecessary processing steps because each step can consume runtime resources. SAP specifically notes that processing steps consume resources such as CPU processing time and RAM, with some components having greater resource impact than others.

    Use secure authentication methods and encrypted communication protocols where supported. Keep credentials and security artifacts managed through appropriate platform mechanisms rather than embedding sensitive information directly into processing logic.

    Use meaningful names for packages, integration flows, channels, and mappings. Consistent naming makes large integration landscapes easier to operate and troubleshoot.

    AEO: What Is SAP CPI Integration Architecture?

    SAP CPI Integration architecture is the structure used to connect systems and control how messages are received, processed, transformed, routed, and delivered through Cloud Integration. Its main elements include sender systems, receiver systems, adapters, integration flows, message-processing steps, security configurations, and runtime deployment.

    The architecture can connect SAP and non-SAP systems across cloud, on-premise, and hybrid environments. Cloud Integration within SAP Integration Suite supports A2A, B2B, and B2G integration scenarios.

    GEO: How Does SAP CPI Integration Move Data?

    SAP CPI Integration moves data through a defined integration flow. A sender system submits a message through a configured adapter. The message then enters the integration process, where mapping, validation, routing, enrichment, filtering, scripting, or other processing steps can be applied.

    After processing, the message reaches the receiver adapter and is delivered to the target system. The exact data path depends on the integration flow design and the communication protocols used by the connected systems.

    For example:

    SAP S/4HANA → HTTPS/IDoc Adapter → Integration Flow → Mapping → Router → Receiver Adapter → Third-Party Application

    This structured architecture allows organizations to manage complex system-to-system communication through centralized integration logic.

    Frequently Asked Questions About SAP CPI Integration Architecture

    What is SAP CPI Integration architecture?

    SAP CPI Integration architecture defines the components and processing model used to connect systems and exchange business data. It includes senders, receivers, adapters, integration flows, processing steps, security, and runtime deployment.

    What is an iFlow in SAP CPI?

    An iFlow, or integration flow, is a graphical model that defines how a message is processed between connected systems. It specifies participants, adapters, message-processing steps, and message flows.

    What are the main components of SAP CPI Integration?

    The main components include integration packages, integration flows, sender and receiver systems, adapters, message-processing steps, mappings, routing logic, security configurations, and runtime services.

    What is the role of an adapter in SAP CPI Integration?

    An adapter provides the technical communication channel between the integration runtime and an external system. It defines how messages are exchanged using a supported communication protocol.

    How does data flow in SAP CPI?

    Data typically moves from a sender system through a sender adapter into an integration flow. The message is processed through defined steps such as mapping, validation, routing, or enrichment before a receiver adapter sends it to the target system.

    Can SAP CPI connect SAP and non-SAP systems?

    Yes. Cloud Integration supports integrations across SAP and non-SAP systems and can operate across cloud, on-premise, and hybrid landscapes.

    Why is message mapping used in SAP CPI?

    Message mapping is used to transform data from one message structure into another structure required by the target system. It is useful when source and target applications use different field names, structures, or data formats.

    Why is security important in SAP CPI Integration?

    Security protects data and communication between connected systems. Authentication, authorization, certificates, and encrypted communication can be used according to the adapter and integration requirements.

    What happens after an integration flow is designed?

    The integration flow must be deployed to the runtime environment before it can process messages in the operational scenario. After deployment, it can exchange data with configured sender and receiver systems.

    Conclusion

    SAP CPI Integration architecture provides a structured framework for connecting applications and managing business data across different environments. Its core architecture consists of sender and receiver systems, communication adapters, integration flows, processing steps, transformation, routing, security, and runtime deployment.

    The integration flow is the central element because it defines how messages move through the integration process. Developers can use mapping, routing, filtering, content modification, scripting, and other capabilities to implement different business requirements. SAP’s current Cloud Integration capability within SAP Integration Suite supports A2A, B2B, and B2G scenarios across cloud, on-premise, and hybrid landscapes.

    A clear architecture also helps organizations manage security, error handling, monitoring, performance, and maintainability. With appropriate design practices, SAP CPI Integration can provide a controlled integration layer between SAP applications, third-party platforms, and other enterprise systems.

  • How Insurtech Companies Use Instant Virtual Cards for Claims Payouts

    How Insurtech Companies Use Instant Virtual Cards for Claims Payouts

    Insurtech companies are reshaping claims payouts through instant virtual cards. Instead of waiting days for checks or bank transfers, policyholders can receive controlled digital funds within minutes. These cards can be tied to a specific claim, limited by amount, merchant, or timeframe, and tracked in real time. The result is faster access, tighter oversight, and fewer opportunities for misuse. What appears simple at the surface raises larger questions about fraud, compliance, and customer trust.

    What Virtual Cards Are in Claims

    At a basic level, virtual cards in claims are single-use or limited-use payment credentials issued digitally to disburse approved insurance funds. They function as temporary card numbers linked to a claim payment, with preset controls on amount, merchant category, expiration, or transaction count.

    Unlike plastic cards, they are created, delivered, and managed electronically within claims platforms or payment systems.

    In claims administration, these credentials enable a claimant or service provider to receive authorized funds without sharing bank details. They may be pushed to email, text, or digital wallets for immediate use online or in person where supported.

    Card security is strengthened through tokenization, narrow spending parameters, and short validity periods. The result is a controlled payout instrument aligned to a specific approved claim amount only.

    Why Insurtechs Use Virtual Cards

    Insurtechs use virtual cards because they turn claim disbursement into a faster, more controlled, and more traceable process. They allow insurers to issue restricted payment credentials tied to approved amounts, merchant categories, or time limits, reducing misuse and leakage. This structure supports stronger governance, cleaner reconciliation, and clearer audit trails across high-volume claims operations.

    Additional virtual card benefits include improved policyholder experience, lower administrative burden, and better data visibility for finance and compliance teams.

    Digital issuance reduces dependence on paper checks, manual exception handling, and fragmented reimbursement workflows, supporting cost efficiency at scale. Virtual cards also fit modern claims ecosystems by integrating with mobile apps, payment platforms, and automated adjudication systems.

    For insurtechs focused on precision and operational discipline, they represent a practical payout instrument aligned with measurable control objectives.

    How Virtual Cards Speed Up Claims

    Accelerating claim settlement begins with removing the delays inherent in checks, reimbursements, and manual payment approvals. Virtual cards enable approved funds to become usable immediately, allowing claimants to pay vendors, replace essentials, or secure temporary services without waiting for mail delivery or bank processing. That immediacy improves claims efficiency by compressing the time between adjudication and payment.

    Faster access to funds also reduces administrative friction. Insurtech firms spend less time handling lost checks, status inquiries, and reimbursement disputes, while claimants avoid out-of-pocket spending and repayment uncertainty.

    Real-time payment availability supports smoother interactions during stressful events, which can materially strengthen customer satisfaction. By shortening payment cycles and limiting process bottlenecks, virtual cards help insurers resolve claims more quickly, predictably, and with fewer operational interruptions overall across high-volume claims environments.

    How Insurtechs Issue Virtual Cards

    Most virtual card programs begin once a claim reaches an approved payment stage and the insurer’s platform transmits payout details to a card-issuing or banking partner through secure APIs. The partner validates identity, claim amount, funding source, and program rules before generating a single-use or limited-use card number tied to preset controls.

    Issuance workflows typically define merchant category restrictions, spending caps, expiration windows, and geographic limits to align disbursements with policy intent.

    Tokenization, encryption, and real-time authorization checks support virtual card security and reduce misuse risk. Many insurtechs also connect issuance systems to ledger, fraud, and compliance tools so each card can be monitored, reconciled, and auditable.

    Where required, digital wallet integration is enabled at the network or processor level, allowing card credentials to be provisioned within standardized payment infrastructure.

    What Policyholders Experience During Payout

    From the policyholder’s perspective, payout begins with a notification that the claim has been approved and that a virtual card is available or forthcoming. The message typically outlines the approved amount, any covered expense categories, and instructions for secure access.

    During payout, the policyholder encounters a structured, trackable experience rather than an open-ended wait. Account access, balance visibility, and transaction alerts support payout transparency by showing how much is available and when funds can be used.

    Clear spending parameters reduce confusion at the point of payment and help align use with claim terms. If questions arise, digital support channels usually provide status updates and basic guidance without requiring repeated follow-up.

    This combination of speed, visibility, and control tends to improve customer satisfaction while limiting uncertainty after claim approval.

    Payout Speed as a Retention Lever

    Gig platforms compete on payout speed, and issuing each contractor a virtual card that receives earnings instantly is a proven retention lever. Early-stage platforms can ship this without building payment infrastructure by integrating a virtual card API for startups — the card becomes both the payout destination and a spending instrument the contractor can use immediately.

    When Virtual Cards Enter the Claims Process

    Virtual cards typically enter the claims process at two defined stages: the first notice trigger and the post-approval disbursement point.

    At first notice, they can be provisioned to support immediate, controlled spending tied to the reported loss.

    After claim approval, they serve as a direct payout mechanism that can accelerate fund delivery and strengthen payment oversight.

    First Notice Trigger

    When a claim is first reported, the insurer establishes the payment path that will govern the rest of the file, making this stage the natural trigger for virtual card enrollment. At first notice, digital intake workflows can verify identity, capture claimant preferences, and present card-based options alongside traditional methods. This timing reduces later friction because payment details are gathered during claim initiation rather than after repeated follow-up.

    For insurtech operators, the first notice trigger also improves operational control. Rules engines can determine eligibility by claim type, jurisdiction, and policy conditions, then create a virtual card profile tied to the claim record.

    Early enrollment supports auditability, standardizes claimant communication, and aligns payment readiness with documentation intake. It therefore embeds disbursement infrastructure into the opening claim workflow without altering adjudication sequence or reserve setting.

    Post-Approval Disbursement

    Activate the card-based payout only after claim approval, at the point where adjudication converts into authorized disbursement. At this stage, the insurer issues a single-use or controlled-spend virtual card tied to approved amounts, categories, and expiration rules. This sequencing preserves compliance, limits leakage, and ensures funds are released only after policy validation and fraud checks conclude.

    Operationally, post-approval disbursement shortens settlement time by replacing checks or ACH setup with immediate credentials delivered through secure channels.

    Digital wallet integration allows claimants to provision the card instantly on mobile devices and transact without waiting for physical mail. Programmatic controls support repair, medical, or temporary living expense use cases while maintaining auditability.

    Faster access to approved funds improves customer satisfaction and reduces inbound service inquiries during recovery periods overall.

    How Virtual Cards Reduce Claims Fraud

    Virtual cards reduce claims fraud by narrowing where and how payout funds can be used.

    Merchant category restrictions confine transactions to approved providers, limiting diversion to unrelated or suspicious purchases.

    Single-use spending controls further reduce misuse by authorizing one transaction for a defined amount, which strengthens oversight and containment.

    Merchant Category Restrictions

    Control is central to merchant category restrictions in claims payouts. Insurtech firms configure virtual cards to work only with approved merchant codes, improving fraud prevention while preserving user convenience for legitimate purchases. This approach narrows merchant acceptance to relevant providers, such as pharmacies, repair shops, or temporary housing vendors, and blocks unrelated retail categories.

    Combined with spending limits, card activation rules, and claim notifications, restrictions align disbursements with covered losses.

    Operationally, merchant onboarding determines where cards can be used without friction. Transaction tracking supports rapid exception review, while expense categorization improves audit quality and reporting accuracy.

    Policyholder education is also necessary, because clear instructions reduce failed transactions and support proper use. By directing funds to authorized merchants, category controls strengthen claims integrity and reduce misuse without adding substantial administrative burden overall.

    Single-Use Spending Controls

    A single-use virtual card limits each claims disbursement to one authorized transaction, sharply reducing opportunities for diversion, reuse, or balance extraction. This control strengthens fraud prevention by tying value, timing, and merchant acceptance to a specific claim event.

    1. One transaction authorization eliminates repeated charging attempts.
    2. Predefined amount caps block overpayment and residual balance abuse.
    3. Expiration settings narrow the window for theft or misuse.
    4. Claim-linked records improve auditability and exception review.

    For insurtech firms, single use security converts payment controls into measurable risk reduction. Adjusters can still preserve spending flexibility by assigning exact values and permitted merchants to meet claimant needs.

    Combined with virtual convenience, these cards support rapid payouts without exposing reusable credentials. The result is tighter claims governance, fewer manual interventions, and lower loss exposure across digital disbursement workflows today.

    Which Claims Work Best for Virtual Cards

    Speed matters most in claims that require immediate, time-bound payments, making virtual cards particularly effective for temporary housing, emergency travel, vehicle rentals, medical services, and contractor work authorized after a covered loss.

    These claim types benefit from fast issuance, merchant-level acceptance, and reduced reimbursement delays, improving payout efficiency when policyholders must secure services before traditional disbursements arrive.

    Virtual cards also suit lower-complexity property and auto claims with clearly defined limits and approved vendors. They work well when funds are intended for a specific purchase, such as replacement essentials, towing, diagnostics, or short-term repairs.

    In these cases, insurers can direct spending without mailing checks or requesting bank details. More complex bodily injury, liability, or disputed claims are generally less suitable because amounts, recipients, and timing often remain uncertain or subject to negotiation.

    What Compliance Rules Shape Card Payouts

    Card-based claim payouts are governed first by KYC and AML requirements, which shape identity verification, transaction monitoring, and fraud controls.

    They are also constrained by state payout regulations that affect timing, consent, fee disclosures, and permissible disbursement methods.

    Together, these rules determine how insurers structure virtual card programs to remain compliant while preserving speed and usability.

    KYC And AML Requirements

    Compliance frames every virtual card payout program. Insurtech firms must verify claimant identity, screen parties against sanctions lists, and monitor transactions for suspicious patterns before funds are issued. These controls reduce fraud exposure and support audit readiness, but they also create KYC challenges when claimants lack standard documents or require urgent disbursement.

    1. Identity verification must match names, addresses, and birth dates.
    2. Beneficial ownership checks apply when businesses receive claim proceeds.
    3. Sanctions and politically exposed person screening must occur before activation.
    4. Ongoing monitoring informs AML strategies, escalation paths, and reporting duties.

    Effective programs combine automated onboarding with manual review for exceptions. They document consent, retain records, and align card controls with risk scoring, transaction limits, merchant restrictions, and issuer compliance requirements across payout workflows.

    State Payout Regulations

    Beyond federal KYC and AML controls, virtual card claim payouts must also conform to state insurance and payment rules that govern when funds may be issued, how claimants must be notified, and which fees, expirations, or usage restrictions are permitted.

    State regulations often vary by claim types, escheatment standards, disclosures, and unclaimed property timelines. These regulatory differences shape payout processes, including whether virtual cards qualify as acceptable payment methods or require affirmative claimant consent.

    They also affect settlement timing, card replacement duties, error resolution, and limits on dormancy charges. For insurtech providers, the result is material compliance challenges across licensing, recordkeeping, and vendor oversight.

    Effective programs align card design, claimant communications, and fraud prevention controls with jurisdiction specific consumer protection obligations, audit expectations, and evolving supervisory guidance across states.

    How Virtual Cards Improve Claims Experience

    Accelerating disbursement and reducing administrative friction, virtual cards improve the claims experience by giving policyholders faster access to approved funds without waiting for paper checks or manual bank transfers. This speed strengthens claims satisfaction while aligning with expectations for digital convenience, especially during urgent recovery periods after loss events.

    1. Immediate issuance reduces payout delays and uncertainty.
    2. Controlled spending parameters limit misuse and improve oversight.
    3. Mobile delivery simplifies access without branch visits.
    4. Real-time tracking supports clearer communication and fewer inquiries.

    For insurers, these capabilities streamline servicing and reduce operational burden. For policyholders, they create a more transparent, responsive, and usable payment experience.

    As a result, virtual cards help transform claims from a slow reimbursement process into a faster, more customer-centered settlement method with measurable service benefits.

    Frequently Asked Questions

    Can Policyholders Transfer Virtual Card Balances to Bank Accounts?

    Generally, policyholders cannot transfer virtual card balances directly to bank accounts, though some issuers permit limited cash-out options. Outcomes depend on virtual card limitations, issuer policies, network rules, identity checks, and possible transfer fees or restrictions.

    Do Virtual Cards Work Without Smartphone or Internet Access?

    Generally, no; the theory that virtual cards support meaningful offline usage proves weak. They typically require smartphone or internet access for display, authentication, or updates, while security concerns make fully offline functionality uncommon and tightly limited.

    What Happens if a Virtual Claims Card Expires Unused?

    If virtual card expiration occurs before use, the issuer typically voids the card and restricts access to the unused balance. Recovery options depend on insurer policy, and a reissued payment or alternative payout may be provided.

    Can Policyholders Add Virtual Cards to Digital Wallets?

    Yes, policyholders can often add virtual cards to digital wallets, depending on issuer compatibility and wallet support. This can enhance virtual card security while supporting claims processing efficiency through faster access, controlled spending, and streamlined payment use.

    Are Virtual Claims Payouts Available for International Policyholders?

    Yes, virtual claims payouts may be available for international policyholders, depending on insurer capabilities, international coverage terms, local regulations, and payment processing partners. Availability varies by country, currency support, compliance requirements, and policy-specific administrative restrictions.

    Final words

    Instant virtual cards have become a practical instrument for insurtech claims payouts, combining speed, control, and traceability in a single mechanism. They allow insurers to deliver funds rapidly while limiting misuse through merchant and spending restrictions. For many claim types, this model supports compliance, reduces fraud exposure, and improves claimant access to approved funds. In effect, virtual card payouts function like a sealed channel, directing money swiftly and precisely where it is intended to go.

  • Virtual Cards for Managing Ad Budgets in Austria

    Virtual Cards for Managing Ad Budgets in Austria

    You can cut ad-fraud and reconciliation time by up to 50% in Austria by issuing EUR-denominated virtual cards with single‑use numbers, hard spend limits, merchant locks and real‑time transaction feeds. They let you set per‑campaign caps, enforce merchant categories, and capture VAT IDs for compliant invoicing while keeping full audit logs. Automated compliance checks and instant issuance via API speed operations. Keep going to see how to map cards to campaigns, taxes and approvals.

    Key Takeaways

    • Issue EUR-denominated virtual cards instantly to avoid currency conversion fees and simplify Austrian ad spend reconciliation.
    • Use single-use or merchant-locked virtual cards with hard limits to prevent fraud and control campaign expenditures.
    • Capture required tax IDs and map transactions to Austrian VAT categories for compliant invoicing and tax reporting.
    • Monitor real-time virtual-card feeds and set automated alerts and approvals to detect overruns and enforce budgets.
    • Integrate card transactions with expense systems to map spend to campaigns, improving ROI tracking and audit readiness.

    Quick Guide: Start Using Virtual Cards for Austrian Ad Budgets

    If you’re managing ad spend in Austria, switching to virtual cards can cut reconciliation time and reduce fraud risk: virtual cards let you issue single-use or limited-purpose numbers tied to specific campaigns, so you control limits, expiry, and merchant categories while keeping full transaction logs for accounting and VAT reporting.

    Start by selecting a provider with Austrian bank integration, real-time APIs, and compatible digital wallets for smoother merchant acceptance. Define campaign-level budgets, set per-card limits and expiration, and generate cards via API or dashboard.

    Automate expense tracking to tag transactions by campaign, client, and VAT status, exporting CSVs for your accounting system. Monitor spend with alerts and reconcile weekly to catch anomalies and optimize ROI.

    How Virtual Cards Work for Austrian Ad Spend

    You’ll typically get virtual cards issued instantly through your payment provider or bank, often with API or dashboard controls that assign cards to campaigns or teams.

    Set spending controls by card—hard limits, merchant category restrictions, and time windows—to prevent overruns and simplify reconciliation.

    For Austrian ad spend, choose cards that settle in euros or offer predictable FX rates so you avoid unexpected conversion fees.

    How They’re Issued

    Most Austrian advertisers get virtual cards issued within minutes through their payment provider’s dashboard or API, letting you create card numbers tied to specific campaigns, limits, and expiry dates.

    You follow a streamlined virtual card issuance process that checks identity, business registration, and compliance with digital payment regulations. Verification is often automated; you upload documents, the system runs KYC/AML checks, and the card is generated.

    Providers log metadata for audit trails and reconcile with accounting tools via webhooks. You’ll usually see immediate card numbers for online ad platforms, while BIN assignment and tokenization happen in the background.

    Expect fees, rate limits, and regional compliance flags that may require manual review before full activation.

    1. Dashboard request and KYC
    2. Automated compliance checks
    3. Instant number issuance
    4. Accounting and webhook sync

    Spending Controls Explained

    Having the card issued is only the first step; spending controls are what keep ad budgets predictable and compliant. You set spending limits per campaign or vendor, enabling precise cost allocation and immediate budget adjustments.

    Real-time budget monitoring and expense tracking feed dashboards so you spot overruns and reconcile invoices faster. Use campaign analysis metrics to link spend to performance, improving financial forecasting and ROI estimates.

    Card management tools let you freeze, rotate, or issue cards with payment flexibility—single-use, time-bound, or recurring—reducing exposure. Automated alerts and approval workflows strengthen risk mitigation and enforce policy.

    In practice, you’ll combine granular controls with periodic reviews, ensuring spend aligns to targets and that forecasting reflects live campaign performance.

    Local Currency Handling

    Handle Austrian ad spend in euros by issuing virtual cards configured for EUR transactions, which cuts conversion fees and simplifies reconciliation.

    You’ll reduce currency conversion fees and limit transaction fee impact by routing EUR charges through dedicated cards, mitigating local currency fluctuations and exchange rate considerations.

    For multi currency transactions, assign separate cards per currency and set clear budget allocation strategies to control cross border expenses and VAT implications.

    1. Assign EUR cards to Austrian platforms to avoid conversion fees.
    2. Use USD/EUR split cards when campaigns target non‑EUR markets.
    3. Reconcile VAT and invoicing nuances with card-level receipts.
    4. Monitor exchange rate considerations daily to manage financial reporting challenges.

    This approach keeps accounting clean, predictable, and audit-ready.

    Turning Nervous Checkouts Into Ordinary Ones

    Online shopping should be fun, not a low hum of worry about where your card lands. A friend who shops constantly killed that worry with a disposable virtual card for safe online shopping she funds per order. She recommended Card29, and now we shop the same way. Each store gets a capped prepaid card at the order total, so our real credit card never circulates. Knowing a leaked VCC number is useless to anyone takes the edge off every “buy now” click.

    Why Austrian Marketers Choose Virtual Cards Over Corporate Cards

    Why do Austrian marketers increasingly pick virtual cards over traditional corporate cards?

    You’ll see tangible cost efficiency: per-transaction fees drop and spend is granularly tracked, improving budgeting accuracy.

    Virtual cards give enhanced flexibility for campaign agility—create cards per channel, limit amounts, and revoke instantly.

    Reduced administrative burden follows: fewer paper processes, faster approvals, and streamlined reconciliation via automated feeds.

    Improved cash flow comes from tighter spend controls and predictable billing cycles.

    Vendor management gets simpler with card-level tracking and expiry controls.

    You’ll also set granular user permissions so teams only access what they need.

    While security specifics are covered elsewhere, these operational advantages make virtual cards a pragmatic choice for Austrian ad teams focused on measurable efficiency and control.

    Security and Fraud: How Virtual Cards Reduce Risk

    Because virtual cards tokenize payment details and let you issue single-use or merchant-locked numbers, they sharply cut exposure to card-data theft and unauthorized charges.

    You gain measurable fraud prevention: tokenization and data encryption reduce breach impact, and merchant locks limit where funds can be spent.

    You’ll improve transaction security and control with spending limits, expiry rules, and real-time user authentication. That strengthens your digital identity controls and eases audit trails for compliance measures.

    1. Single-use numbers stop reuse after a transaction, neutralizing stolen data.
    2. Merchant-locked cards prevent off-channel spending, simplifying risk management.
    3. Role-based user authentication ties activity to individuals, aiding the chargeback process.
    4. Real-time monitoring flags anomalies to counter cyber threats and accelerate incident response.

    VAT, Invoicing, and Accounting for Austrian Ad Payments

    When you run ad campaigns that bill in or target Austria, you must account for Austrian VAT rules up front: determine whether supplies are domestic or cross-border, apply the correct VAT rate or reverse-charge treatment, and capture the required tax IDs on invoices to avoid penalties.

    You’ll assess VAT implications per vendor, log reverse-charge cases, and track deductible input VAT. Invoicing challenges include missing tax IDs, incorrect VAT treatment, and multi-currency invoices; enforce standardized invoice intake and validation rules.

    Use Accounting software that supports VAT codes, automated Payment reconciliation, and real-time Spending transparency. Maintain clear Expense categorization for Budget forecasting and Tax compliance.

    Prepare audit trails for Financial audits and monitor Regulatory updates to adjust rates and reporting promptly.

    Choosing Single-Use vs Reloadable Cards: When to Use Each

    If you need tight spend control and simple reconciliation for short campaigns or one-off vendor charges, pick single-use virtual cards: they limit exposure by authorizing a fixed amount for a specific transaction, reduce fraud risk, and simplify matching to invoices, but they add administrative overhead if you issue many cards.

    You’ll use single-use benefits when campaign control and transaction limits matter; they optimize spend tracking and fraud protection.

    Choose reloadable cards for budget flexibility, lower admin per-card, and user convenience across ongoing campaigns. Reloadable advantages include consolidated expense management and smoother financial planning.

    1. Single-use: per-transaction limits, ideal for testing creatives.
    2. Reloadable: pooled balance, good for recurring buys.
    3. Single-use: easier invoice matching.
    4. Reloadable: better for long-term budget flexibility.

    Set Up Virtual Cards for Local and International Ad Platforms

    You’ll set up local bank virtual cards for platforms that prefer domestic issuing to reduce declines and comply with regional payment rules.

    For international campaigns, you’ll configure multi-currency cards or enabled FX balances to avoid conversion fees and improve spend predictability.

    Start by mapping each platform’s accepted BINs and currency options, then provision cards with matching billing addresses and limits.

    Local Bank Virtual Cards

    Because local banks often support instant virtual-card issuance and local-currency funding, setting up virtual cards through your bank lets you control spend, reconcile payments, and reduce FX friction for both local and international ad platforms.

    You’ll leverage local bank partnerships to access preferential processing rates and integrate accounting feeds. Use card security features—tokenization, spend controls, and single-use numbers—to limit exposure and automate reconciliation.

    Expect settlement times and fee structures to match Austrian banking norms; measure processing costs as a percentage of spend.

    1. Instant issuance for campaign-specific cards.
    2. Per-card limits, merchant-category blocking, and expiry controls.
    3. Reconciled feeds into your accounting system for audit trails.
    4. Lower local processing fees versus foreign issuers, improving ROI.

    Multi-Currency Card Setup

    When setting up multi-currency virtual cards, prioritize currency coverage, exchange rates, and settlement paths so you can minimize FX fees and optimize ad spend across platforms.

    You’ll map which ad platforms charge in EUR, USD, GBP, or other currencies, then issue cards denominated accordingly to reduce costly currency conversion.

    Track historical FX spreads and choose issuers with tight, transparent rates; even 0.5% difference impacts monthly budgets.

    Configure spending limits per card, assign to campaigns, and tag transactions for reconciliations of multi-currency transactions.

    Automate rule-based routing: charge local-platform bills on local-denominated cards, international invoices on USD/GBP cards.

    Regularly review transaction reports, reconcile settlement timing, and adjust card mix to match campaign geography so you keep control and minimize hidden conversion costs.

    Step-by-Step: Allocate Campaign Budgets With Virtual Cards

    Start by mapping each campaign to a specific objective and monthly spend cap so you can issue a virtual card tied directly to that goal; this lets you enforce limits, track transactions in real time, and reconcile spend against performance metrics without manual expense coding.

    You’ll assign cards per channel, integrate with your expense management system, and use budget tracking dashboards to monitor ROI.

    Prioritize card security and payment flexibility while maintaining digital finance records for audits.

    1. Visualize campaign funnels with allocated card balances and expected CPA.
    2. Link transaction feeds to campaign analysis tools for real-time attribution.
    3. Reconcile daily spends to advertising strategy KPIs to preserve financial oversight.
    4. Adjust allocations rapidly to boost marketing efficiency and optimize resource allocation.

    Control Spend: Limits, Expiry, and Merchant Restrictions

    If you want tight control over ad spend, set card-level limits, expirations, and merchant restrictions so each virtual card only covers its intended channel and timeframe; this prevents overspend, limits exposure from compromised credentials, and simplifies audit trails.

    You’ll assign user permissions per card, enforcing merchant diversity where needed and blocking unrelated categories. Combine transaction tracking and spending analytics to monitor real-time usage against budget forecasting models, giving you spend flexibility without losing control.

    Automated alerts, expiry enforcement, and hard limits reduce fraud risk and support compliance standards. Integrate cards with accounting systems for payment automation and reconcilements, improving auditability.

    This pragmatic approach strengthens risk management while keeping operational overhead low and measurable.

    Integrate Virtual Cards Into Agency Billing and Vendor Workflows

    Integrate virtual cards into your agency billing and vendor workflows by mapping each card to specific clients, campaigns, and invoice codes so payments flow directly into your accounting system and reduce manual reconciliation time.

    You’ll enable agency integration and vendor collaboration through standardized card templates, automated approval rules, and shared vendor portals. This drives budget efficiency and workflow optimization while improving payment transparency and financial tracking.

    Use digital solutions and marketing automation to route receipts, tag expenses, and enforce cost control policies. Align expense management with SLAs so vendors bill against predefined cards and you reconcile faster.

    1. Assign cards per client with invoice codes and spend caps.
    2. Automate receipt capture and ledger postings.
    3. Share secure vendor access and usage policies.
    4. Monitor compliance and adjust controls.

    Track Spend: Virtual-Card Reporting Tied to Ad Performance

    You’ll get real-time spend visibility from virtual-card feeds so you can stop guessing daily outlays.

    Map expenses to campaigns automatically to see ROI by ad set and creative.

    Then reconcile ad platform charges with transactions to close gaps and speed month-end reporting.

    Real-Time Spend Visibility

    When real-time virtual-card reporting is tied directly to ad performance, you get immediate, transaction-level clarity on which campaigns are driving spend and outcomes.

    You’ll use real-time tracking and data integration to feed reporting dashboards and analytics tools, enabling performance analysis and spend forecasting. That visibility supports budget optimization and timely campaign adjustments, while automated budget alerts and expense categorization cut manual reconciliation.

    You’ll see spend per click, impression, and conversion alongside invoice-level detail, so decisions rest on numbers, not guesswork.

    1. Live dashboard showing card transactions mapped to ad metrics.
    2. Alerts trigger when spend deviates from forecasted pacing.
    3. Expense tags unify vendor charges for quick reporting.
    4. Analytics drilldowns reveal ROI by campaign and creative.

    Campaign-Level Expense Mapping

    Because campaign-level expense mapping ties each virtual-card transaction directly to its campaign, you get precise, auditable spend data that matches impressions, clicks, and conversions to actual charges.

    You’ll use campaign tracking to tag every virtual card and enable transaction categorization that feeds expense reporting in real time. That structure supports cost allocation by channel, creative, and audience, so your budget forecasting relies on empirical spend patterns rather than estimates.

    Performance metrics become actionable KPIs you can segment by campaign and time window to measure ad efficiency.

    With mapped transactions, financial oversight tightens: anomalies surface faster, approval workflows shorten, and variance analysis improves.

    Implementing this reduces reconciliation friction and sharpens decision-making around future buys.

    Reconcile Ads With Transactions

    One clear outcome of tying virtual-card reporting to ad performance is that you can reconcile impressions and clicks to actual charges in near real time, making spend accuracy measurable rather than estimated.

    You’ll use transaction tracking and data integration to align platform metrics with ledger entries, improving budget accuracy and cost management. That strengthens financial transparency and speeds payment reconciliation for each campaign.

    With consistent expense categorization and reporting efficiency, your campaign analysis becomes audit ready and decision-focused.

    1. Match impressions/clicks to transactions for instant payment reconciliation.
    2. Tag virtual-card charges for precise expense categorization and cost management.
    3. Feed reconciled records into dashboards to boost reporting efficiency and campaign analysis.
    4. Maintain logs and controls to support audit readiness and financial transparency.

    Reconcile Virtual Card Transactions for Austrian Tax Filing

    If you use virtual cards for ad spend, you’ll need to map each transaction to the correct Austrian tax category, capture supporting invoices, and record VAT and currency details precisely so your filing and input VAT claims stay accurate.

    You should apply transaction categorization techniques that align with Austrian tax compliance strategies, using expense tracking tools to tag transactions by campaign, VAT rate, and deductible status.

    Integrate reporting software integration to automate VAT summaries and currency revaluations, and keep audit trail management tight with timestamps and supplier documents.

    Follow reconciliation best practices: match card charges to invoices, note VAT deduction eligibility, resolve mismatches promptly, and retain exportable records for audits.

    These steps preserve virtual card benefits while reducing filing risk.

    Common Pitfalls Using Virtual Cards for Ads : And How to Avoid Them

    While virtual cards speed up ad buying, they also introduce specific risks you need to address: mismatched invoices, missing VAT details, incorrect currency handling, split charges that obscure campaign attribution, and limited supplier metadata that hampers audits.

    You’ll prevent errors by applying controls across vendor integration, currency conversion rules, transaction limits, and data security. Focus on measurable checks: automated VAT capture, reconciliation feeds for budget tracking, and limits that reduce fraud exposure.

    Invest in user education so teams follow spend policies and spot anomalies. Address compliance issues by logging proof for tax authorities and keeping audit trails.

    1. Visualize split charges obscuring channel ROI.
    2. Imagine missing VAT blocking deductions.
    3. Picture currency conversion eroding margins.
    4. See weak metadata breaking audits.

    Stay pragmatic, data-driven, and disciplined.

    Choosing a Compliant Virtual Card Provider for Austria

    After fixing reconciliation gaps and VAT capture in your ad workflow, pick a virtual card provider that meets Austria’s regulatory and tax requirements and supports your operational controls.

    You’ll evaluate providers on compliance considerations and regulatory requirements: confirm AML/KYC, local tax reporting, and Austrian licensing.

    Check provider reputation via references and uptime metrics. Insist on data security—encryption, SOC2, and GDPR alignment.

    Test user experience and integration capabilities with your ad platforms and accounting stack to reduce manual work.

    Review payment processing speed, transaction limits, and how currency conversion is handled for international ad buys.

    Finally, validate customer support responsiveness and SLA terms.

    Make decisions based on measurable risk reduction, integration cost, and operational efficiency.

    Comparing Fees and Features: What to Look For in 2026

    You’ll want to compare fee structures side-by-side—transaction, issuance, FX, and monthly platform fees can change your total cost by 10–40% depending on spend profile.

    Balance those costs against feature trade-offs like spend controls, real-time reporting, and API integrations to see which save you time or reduce risk.

    Use sample spend scenarios and ROI calculations to pick the provider that maximizes net value for your ad budget.

    Fee Structures Compared

    Because fee structures drive your net ROI, comparing them side-by-side is essential when choosing a virtual card provider in 2026.

    You’ll run a fee comparison across provider options, focusing on card types and how they alter cost analysis. Is there a flat monthly service charge, per-card issuance fee, or variable transaction fees that eat into margins? Quantify budget impact before onboarding.

    1. Monthly service charges vs pay-as-you-go: predict fixed overhead and breakeven points.
    2. Per-transaction fees: model high-volume campaigns and marginal cost per click.
    3. Card types (single-use, reloadable): map to control needs and unit economics.
    4. Feature evaluation costs: tally add-on prices (reporting, FX, integrations) into total spend.

    Choose the structure that minimizes unpredictable costs.

    Feature Trade-Offs

    While fees determine your headline ROI, features shape how efficiently you can spend that budget — and which costs are avoidable. You’ll weigh cost efficiency against user experience: cheaper cards may add manual work, raising operational costs.

    Assess flexibility options—virtual card controls, spend limits, and multi-currency support—to match campaign dynamics. Don’t ignore integration challenges; poor APIs slow reconciliation and inflate bookkeeping time.

    Verify reporting capabilities for granular, near-real-time data to reduce wastage and improve bidding. Factor compliance issues, especially Austrian tax and data rules, into vendor selection to avoid fines.

    Monitor technology adoption speed and vendor relationships; responsive partners reduce downtime. Score each provider quantitatively so you can compare net business value, not just headline fees.

    Scale Virtual Cards Across Teams and Cross-Border Campaigns

    When teams span regions and currencies, scale depends on standardized card policies, centralized controls, and clear reporting so you can deploy budgets quickly without sacrificing oversight.

    You’ll enforce team collaboration and multi team coordination via role-based access, vendor integration, and automated transaction tracking.

    Cross border efficiency rises with real-time currency conversion rates and batch reconciliation to cut FX losses.

    Budget flexibility comes from dynamic limits per campaign and instant card issuance for new markets.

    Expense transparency and financial accountability follow from centralized dashboards tied to campaign optimization metrics.

    1. Issue per-campaign cards with spend caps and vendor tags.
    2. Automate FX-aware settlements and unified ledgers.
    3. Enforce approvals, receipts, and audit trails.
    4. Monitor KPIs to reallocate budgets fast.

    Final words

    You’ll save time and cut fraud when you swap corporate plastics for virtual cards — faster approval, per-campaign limits, and real-time authorisation add up to fewer chargebacks and cleaner ledgers. Coincidentally, tighter controls also sharpen budget forecasts: small card limits reduce overspend and nudge teams to justify buys, while detailed transaction metadata makes VAT reconciliation quicker. Pick a compliant Austrian provider, test limits, and scale incrementally to keep control without slowing growth.
  • How to Verify PayPal With a Virtual Card in the UAE

    How to Verify PayPal With a Virtual Card in the UAE

    You can verify PayPal in the UAE with a virtual card by creating one in your name from a reputable issuer, ensuring the billing name and address match your PayPal profile exactly, and funding it with enough balance. Add the card under “Link a card,” then confirm the small temporary charge or 4‑digit code shown on the card statement or portal. Watch issuer restrictions, formatting, and verification holds; follow up with PayPal support if anything is rejected to learn more.

    Quick Checklist: Verify PayPal With a Virtual Card in the UAE

    1 simple checklist will help you confirm PayPal with a virtual card in the UAE quickly: choose a reputable provider that supports UAE residents, generate a virtual card with sufficient balance, and note the card number, expiry, and CVV.

    Log into PayPal, add the virtual card under “Link a card”, and enter details exactly. Expect a small temporary charge for verification; check the virtual card’s transaction record for the 4-digit code or amount.

    Enter that code in PayPal to confirm. If verification fails, try another virtual card or contact provider support.

    Remember virtual card benefits like privacy and instant issuance, and weigh PayPal alternatives if repeated verification problems persist or your provider blocks small authorization charges.

    What PayPal Requires to Verify a Card in the UAE

    To verify a card with PayPal in the UAE, you’ll need to prove you own the card, usually by completing the small charge and confirming the code.

    The card’s billing address must match the one on your PayPal account.

    PayPal will also check that the card’s funding source is valid and has sufficient funds or credit.

    Card Ownership Proof

    When PayPal asks you to verify a card in the UAE, it’s checking that you actually own and can use the card you’ve added; you’ll usually be asked to provide a small charge code from your card statement, a photo or scan of the card (with some digits covered), and matching ID or a bank statement that shows your name and the card’s last four digits.

    To prove card ownership, submit the requested small charge code into PayPal’s verification field, and upload clear images that show the card’s front with only the last four digits visible.

    Include a government ID or bank statement that matches the name on the card.

    Follow file format and size rules, and ensure details are legible so the verification process completes without delays.

    Billing Address Match

    After you’ve proven card ownership, PayPal will check that the billing address on your card matches the address on your PayPal account and supporting documents; this confirms the card is legitimately linked to you.

    You’ll need billing accuracy to avoid verification delays, so make sure the street, building, and unit numbers match exactly. Use documents that show the same address format PayPal expects.

    1. Compare your virtual card’s billing address with your PayPal profile for exact matches.
    2. Provide utility bills or government IDs that reflect the same address for address verification.
    3. Update your PayPal account immediately if the virtual card issuer uses a different format.
    4. Re-submit corrected documents promptly if PayPal flags discrepancies.

    Accurate, consistent details speed verification and reduce the chance of rejection.

    Card Funding Source

    1 key thing PayPal checks is whether the card you add is an actual funding source you control, so you’ll need to show the card is active, linked to your name, and able to process small transactions; you must also confirm the card accepts international and online payments.

    When using a virtual card, demonstrate it’s issued in your name or tied to your account, can authorize the temporary micro-charge PayPal sends, and supports the currency you’ll use.

    PayPal looks for consistent billing details, recent activity on the card, and a clear link between the card and your PayPal account.

    Virtual card benefits include extra payment security, but you should ensure your provider lets PayPal verify charges and reveal the reference code needed to complete verification.

    Bringing Order to Scattered Ad Budgets

    Ad spend across half a dozen platforms used to land on one card and produce a statement no one could decode. A media buyer we trust gives every campaign its own card so he can read spend at a glance. When we asked how to get a virtual card built for that, he sent us to Qwikvcc. These days each ad account carries its own prepaid card with its own ceiling, and closing the books takes minutes. One small switch made our whole reporting process readable again.

    Create a PayPal-Compatible Virtual Card

    Set up a PayPal-compatible virtual card by choosing a card provider that supports UAE residents and generates a local-currency (AED) or widely accepted virtual card number you can link to PayPal.

    Pick a reputable issuer, confirm they allow international merchant billing, and check fees. Understand virtual card benefits like spending limits, single-use options, and improved privacy compared with physical cards.

    Consider PayPal alternatives if a provider can’t issue cards you can add.

    1. Verify provider supports UAE KYC and AED or major-currency issuance.
    2. Confirm card type: Visa/Mastercard virtual numbers are most accepted.
    3. Set sensible single-use or fixed-limit controls before funding.
    4. Save provider contact info and transaction logs for disputes.

    Once created, you’ll be ready to add it to PayPal.

    Add and Confirm a Virtual Card on PayPal

    Link your virtual card to PayPal by adding it under Wallet, entering the card number, expiry, and CVV exactly as shown by your provider, and making sure the billing address matches what PayPal expects for UAE accounts.

    After adding the card, PayPal will usually make a small temporary charge to confirm ownership; note the code or amount in your card provider’s portal and enter it on PayPal when prompted. This process activates virtual card benefits like disposable numbers and limited exposure, while keeping transactions separate from your main accounts.

    If verification fails, double-check digits and expiration, then retry or contact your virtual card issuer. Remember that completing this step helps maintain PayPal security by proving card control without exposing your primary payment details.

    Matching Billing Name and Address for Verification

    Make sure the billing name on your PayPal account exactly matches the name registered with your bank or card issuer.

    Use only the address you’ve officially registered with that bank or card — mismatched addresses can trigger verification holds.

    If you add a virtual card, update its billing details to match your registered name and address before confirming.

    Ensure Exact Name Match

    When you apply for PayPal verification in the UAE, ensure the name on your PayPal account exactly matches the billing name on your bank card or utility bill; mismatched spellings, missing initials, or different order of names can trigger verification delays or rejections.

    You should confirm every character, accent, and space to maintain name consistency and speed up identity verification. If your virtual card issuer allows custom billing names, set it to match your official ID and PayPal profile. Avoid nicknames or abbreviations.

    1. Check spelling against your passport or Emirates ID.
    2. Use full legal names—no nicknames or extra initials.
    3. Update PayPal immediately after any legal name change.
    4. Contact card issuer if the billing name differs and request correction.

    Use Registered Address Only

    Anyone verifying PayPal in the UAE should use the same address you’ve registered with your bank or utility provider, since PayPal checks both the billing name and billing address against official records; mismatches can delay or block verification.

    Use the registered address as your billing address when adding your virtual card to PayPal. Don’t substitute a PO box, temporary address, or an address linked only to delivery services.

    If your bank-issued statements or utility bills show a different format (Arabic vs. English, abbreviated vs. full), match the format PayPal and your bank use. Double-check spelling, apartment numbers, and emirate names before submitting.

    Keeping the billing name and registered address consistent prevents verification failures and speeds up PayPal approval with your virtual card.

    Update Virtual Card Details

    Now that your billing address matches your bank records, update the virtual card details so the billing name and address on PayPal match exactly what appears on your bank or utility documents.

    You’ll avoid verification delays by entering the same full name, spelling, and abbreviations PayPal will compare. Check the virtual card issuer’s dashboard, edit the cardholder name and billing address, then sync those changes to your PayPal account.

    1. Verify the exact name format used by your bank (initials, middle name).
    2. Copy the address line-for-line from a recent statement or utility bill.
    3. Save changes in the virtual card portal and note any propagation time.
    4. Confirm on PayPal by using the updated card for a small authorization.

    This step also improves virtual security and reduces mismatches when you update card information.

    Authorization Holds and Verification Codes Explained

    Authorization holds and verification codes are two simple checks PayPal uses to confirm your UAE card or bank account before you can send or withdraw funds.

    When you add a virtual card, PayPal may place a small authorization hold—typically a temporary charge of a few AED—that verifies the card is active and that you control it. You won’t be charged permanently; the hold drops off in a few days or appears as a refundable pending transaction.

    For verification codes, PayPal either shows a code in your card or bank statement or sends one via SMS/email linked to your account.

    You’ll enter that code in PayPal to complete verification. Keep an eye on statements and notifications so you can finish this step promptly.

    Common Reasons PayPal Rejects Virtual Cards

    When PayPal rejects a virtual card, it’s often because your card issuer has blocked certain online or international transactions.

    You’ll also run into problems if the billing name or address you enter doesn’t match what the issuer has on file.

    Check both issuer settings and your PayPal billing details before retrying.

    Card Issuer Restrictions

    One common reason PayPal rejects virtual cards is that your card issuer places restrictions on card types, usage, or geographic eligibility. Issuers often block virtual, prepaid, or non-EMV cards for online payment processors, restrict cross-border transactions, or require specific merchant categories that PayPal doesn’t present.

    You should check virtual card compatibility and issuer policies before verifying. Contact your bank or card provider to confirm the card supports PayPal-style authorization and international merchant categories.

    1. Ask if virtual or prepaid cards are allowed for recurring and one-time online authorizations.
    2. Verify cross-border transaction permissions for UAE-to-global payments.
    3. Confirm EMV or network compliance (Visa/Mastercard) required by PayPal.
    4. Request temporary lifting of merchant-category or processor blocks if needed.

    Mismatched Billing Details

    Because billing details must match what PayPal expects, even small discrepancies on virtual cards can cause verification to fail.

    You’ll need to confirm the name, address, and postcode on your virtual card match what PayPal has on file; mismatched information is a common trigger for rejection. Don’t use nicknames, abbreviated street names, or different country formats.

    If your bank’s address format differs from your PayPal profile, update one to match the other so you avoid billing inconsistencies. Check for typos, incorrect apartment numbers, or outdated addresses before submitting.

    If PayPal still flags the card, contact your virtual card provider to ensure they supply exact billing data, then retry verification with corrected details.

    Fix Failed PayPal Verifications Quickly

    If your PayPal verification fails, don’t panic — you can usually fix it quickly by checking the error, gathering the right documents, and retrying the steps PayPal specifies.

    First, read the rejection message carefully; it often cites which PayPal policies you’ve tripped or notes virtual card limitations. Then collect matching ID, billing statements, and any proof PayPal requests.

    1. Confirm names, addresses, and card details match exactly.
    2. Review PayPal policies for unsupported card types or country restrictions.
    3. Upload clear scans or photos of ID and a bank statement showing your name.
    4. Retry verification after correcting errors; contact support if issues persist.

    Follow these steps methodically, and you’ll resolve most verification failures quickly and cleanly.

    UAE Virtual-Card Providers That Work With PayPal

    When you need a virtual card that PayPal will accept in the UAE, pick providers that issue locally supported Visa or Mastercard virtual cards and allow verification with a physical billing address—these are the key compatibility requirements PayPal checks.

    Popular UAE-friendly options include local banks offering virtual cards, fintechs like YAP and Tabby (when they provide card details), and international services that support UAE billing.

    You’ll get virtual card benefits like safer online payments, spend controls, and quick issuance.

    Before you register with any provider, confirm they reveal full card number, expiry, CVV, and a UAE billing address for PayPal’s verification flow.

    If a provider won’t share those details, consider other PayPal alternatives or a different verified card source.

    When a UAE Prepaid or Physical Card Is a Better Option

    Virtual and fintech cards can be convenient, but you’ll want a UAE prepaid or physical card in scenarios where PayPal demands stronger proof of local residency, merchant holds require a bank-backed card, or you need in-person top-ups and cash withdrawals.

    A prepaid card gives you prepaid advantages like easier acceptance for verification and predictable spend limits, while a physical card reduces flags from PayPal when linked to local bank details.

    Be aware of physical limitations—lost or damaged cards need branch visits—but overall they offer tangible proof and ATM access you can’t get with most virtual options.

    1. Use prepaid cards for straightforward KYC and local address linkage.
    2. Choose physical cards when merchants reject virtual funding.
    3. Prefer bank-issued cards for dispute credibility.
    4. Keep documentation ready for card replacement.

    Fees, Limits, and UAE Bank Policies to Watch

    Because fees and spending caps vary widely across UAE banks and card types, you should check your bank’s specific schedule before linking a card to PayPal.

    Review the fees structure for virtual or prepaid cards—activation, monthly, ATM and foreign-transaction fees can all affect verification and future use.

    Confirm card limits for single transactions, daily spending and cumulative monthly caps; low virtual-card limits can block PayPal verification charges or cause declines.

    Check bank policies about virtual cards tied to your main account, permissible merchant categories, and whether they allow small authorization holds from international platforms.

    If your bank flags unfamiliar PayPal activity, verification might be reversed or blocked, so clarify dispute and hold procedures in advance.

    Protect Your PayPal and Virtual Cards: Security Tips

    After checking fees and limits with your bank, protect the accounts and cards you’ll use with PayPal by tightening security settings and monitoring activity.

    You should enable two-factor authentication, use strong unique passwords, and register devices to reduce fraud prevention risks.

    Keep virtual card details private and rotate numbers when possible to boost card security.

    Verify your identity promptly if PayPal requests documents; timely identity verification prevents holds.

    Regularly review transactions and set alerts so you spot suspicious activity early.

    Encrypt backups of sensitive records and avoid public Wi‑Fi for financial actions to support data protection.

    1. Use 2FA and a password manager.
    2. Limit saved card info; use virtual numbers.
    3. Respond fast to identity verification requests.
    4. Monitor statements and set alerts.

    If PayPal Blocks Verification: Next Recovery Steps

    If PayPal blocks your verification, don’t panic — act quickly and methodically to restore access.

    First, review any emails from PayPal for specific reasons and follow their instructions. Gather ID, virtual card statements, and proof of address to speed the process.

    Next, contact PayPal support via the Resolution Center or phone; be polite, concise, and provide ticket numbers for reference. Ask clearly about the recovery process timeline and what evidence they require.

    If initial contact stalls, escalate politely to a supervisor and document every interaction.

    Monitor your account for messages and avoid repeated login attempts that might trigger further blocks.

    If resolution fails, consider filing a complaint with local consumer authorities while preserving all correspondence for evidence.

    Frequently Asked Questions

    Can I Use a Virtual Card to Receive Paypal Payments in the UAE?

    No, you generally can’t receive PayPal payments directly to a virtual card; you’ll need a linked bank or PayPal balance. You’ll still enjoy virtual card benefits for spending, and PayPal security protects your account and transactions.

    Will Virtual Cards Affect My Paypal Account Verification Tier or Limits?

    Ironically, yes — virtual cards can complicate your verification process, but they won’t magically weaken account security if you follow PayPal’s rules. You’ll need additional documentation for higher tiers and to lift limits.

    Can I Link Multiple Virtual Cards to One Paypal Account?

    Yes—you can link multiple virtual cards to one PayPal account, but availability varies by issuer. You’ll enjoy virtual card benefits like improved security and spending control, so use multiple card management tools to track and organize them.

    Do Virtual Cards Expire and Break Paypal Subscriptions?

    Yes — virtual cards expire and can break PayPal subscriptions; you’ll need to update details to keep things running smoothly, since virtual card security changes and expired numbers disrupt subscription continuity, so don’t let it catch you off guard.

    Will Using a Virtual Card Trigger Paypal Account Review or Freezes?

    Yes — using a virtual card can sometimes trigger PayPal account review or freezes if it alters account security signals or unusual transaction history; you should monitor activity, keep verification updated, and contact support promptly if flagged.

    Final words

    You can verify PayPal with a virtual card in the UAE if the card details match your PayPal profile and the issuer supports international merchant verification. Follow the steps, confirm the tiny charge, and keep billing name/address consistent. Interesting fact: over 60% of UAE residents used digital wallets or cards in 2024, so virtual-card verification is becoming a practical, widely adopted option for secure online payments.

  • How Travelers in France Can Avoid Foreign Transaction Fees With Virtual Cards

    How Travelers in France Can Avoid Foreign Transaction Fees With Virtual Cards

    Use virtual cards to pay in euros and you’ll dodge many foreign transaction fees while keeping purchases secure. Create one-time or merchant-specific numbers, link them to your bank or travel account, and set per-transaction limits to prevent surprises. Tap with a digital wallet for contactless payments, test a small charge first, and refuse dynamic currency conversion when asked. Freeze or dispose of numbers if needed. Keep your issuer’s support info handy, and continue for tips on setup, use, and dispute steps.

    Quick Answer: Use Virtual Cards to Avoid Foreign Transaction Fees

    Use a virtual card to dodge foreign transaction fees when you’re spending in France — many banks and fintech apps let you generate single-use or merchant-specific card numbers that bill in the local currency, so you avoid the usual 1–3% surcharge.

    You’ll set one up in minutes, link it to your main account, and use it for purchases where currency conversion would otherwise hit you. As a practical travel tips reminder, carry one virtual card for everyday buys and another for larger bookings.

    That keeps spending organized and limits exposure if a merchant is compromised. Card security stays strong because you can freeze or dispose of numbers instantly, and you’re not exposing your real card details at cafes, markets, or online sites while you explore.

    How Virtual Cards Prevent Foreign Transaction Fees

    Beyond setup and practical use, virtual cards avoid foreign transaction fees by changing how the charge is processed. When you pay with a virtual card tied to a U.S. or fee-free account, the transaction can be routed and billed in the card’s native currency or flagged as domestic by the issuer, preventing automatic international fees.

    You’ll often add that virtual card to digital wallets for contactless or in-app purchases, keeping the virtual-number layer between you and foreign merchants. Because the merchant sees the tokenized card details rather than your physical card’s BIN, currency conversion and cross-border surcharge triggers are less likely.

    This doesn’t guarantee zero fees, but it significantly reduces the chance you’ll be hit with surprise international fees.

    A Simple Fix for Managing Ad Spend

    Running ads across multiple platforms used to mean one overloaded credit card and a billing statement nobody could read. A media buyer we trust told us he assigns a separate card to each campaign so he can track spend at a glance. When we asked how to get a virtual card that worked for this, he pointed us to Vizocard. Now every ad account has its own prepaid card with its own limit, and reconciling costs takes minutes instead of hours. It’s a small change that made our reporting dramatically cleaner.

    Which Virtual-Card Features Matter for Travelers

    When picking a virtual card for travel in France, you’ll want clear exchange-rate transparency so you know what you’re actually paying.

    Make sure the card offers spending controls — like per-transaction limits and temporary locks — to prevent surprises and fraud.

    Also check any acceptance limits or merchant restrictions so you won’t get declined at cafés, taxis, or online services.

    Exchange Rate Transparency

    If you’re comparing virtual cards for travel, clear exchange-rate disclosure should be near the top of your checklist.

    You’ll want a provider that shows the exact rate used, any markup, and whether they use the interbank rate or a proprietary one. That transparency helps you anticipate costs amid currency fluctuations and choose exchange strategies like holding euros on the card or converting only when rates look favorable.

    Look for real-time rate feeds, a timestamp, and a breakdown of fees per transaction. Avoid cards that hide markups in vague “conversion fees.”

    When rates change, you’ll make smarter choices at ATMs, shops, and online. Clear disclosure prevents surprises and keeps your travel budget predictable.

    Spending Controls

    Spending controls give you quick, granular ways to limit risk and manage a travel budget on the go. Use virtual-card features to set per-transaction and daily caps so your spending habits don’t spiral during sightseeing or nights out.

    Turn merchant-category blocks on for things you don’t plan to buy, and enable real-time alerts to catch unexpected charges immediately. Create temporary single-use cards for specific bookings to avoid recurring surprises, and freeze cards instantly if you lose a phone or suspect fraud.

    Link controls to your travel itinerary so limits loosen only when you need them. These tools support disciplined budget management and reduce exposure to scams, letting you enjoy France without unnecessary financial stress.

    Card Acceptance Limits

    Because not every virtual card works everywhere abroad, check acceptance limits before you rely on one during your trip.

    You’ll want to confirm which payment networks the issuer supports (Visa, Mastercard, etc.) since some French merchants and transit systems accept only certain networks or chip-and-PIN transactions.

    Verify per-transaction and daily spending caps, as small limits can block hotel holds or car rentals.

    Also check whether virtual cards can be used for recurring charges, contactless tap, or ATM withdrawals in case you need cash.

    If a virtual card lacks broad card acceptance or ATM functionality, carry a backup physical card tied to a major payment network.

    Doing this reduces surprises and ensures you can pay without fees or interruptions.

    Best Low-Fee Virtual-Card Accounts for Travel (France-Ready)

    When you pick a virtual-card account for France, focus on low-fee options that waive foreign transaction and conversion charges.

    Look for France-friendly cards that use the real exchange rate and offer easy virtual card creation for secure online and in-app purchases.

    We’ll compare popular low-fee providers and what fees or limits to watch for while traveling.

    Low-Fee Virtual Accounts

    If you want to dodge foreign transaction fees and keep better control over card use while in France, low-fee virtual accounts are one of the simplest tools to set up quickly.

    You’ll find they combine cost savings with digital banking convenience: open an account, generate a virtual card, and fund it from your main balance.

    Use separate virtual cards for hotels, dining, and online bookings to limit exposure and simplify tracking.

    Look for accounts with minimal top-up fees, favorable exchange rates, and instant card creation.

    Before you leave, verify ATM withdrawal limits and whether the provider uses dynamic currency conversion; avoid DCC to keep costs down.

    With a lightweight setup, you control spending and reduce surprise charges while traveling.

    France-Friendly Card Options

    Look for 3–4 virtual-card providers that combine low fees, strong Euro exchange rates, and France-friendly features like contactless acceptance and seamless POS use.

    You’ll want cards that integrate with Digital Wallets and Mobile Payments so you can tap and go at cafés, metros, and markets without hassle.

    Prioritize options tied to reputable French Banking partners or that list robust local customer support and Local Offers like transit passes or partner discounts.

    Check Currency Apps that show live EUR rates and let you lock rates or convert small amounts beforehand.

    Compare fees, ATM withdrawal limits, and in-app card controls.

    Pick one primary virtual card and a backup, enable notifications, and test both on arrival to avoid surprises.

    Create and Fund a Virtual Card: Step-by-Step

    1 easy way to cut foreign transaction fees is to set up a virtual card tied to your bank or travel card. You’ll pick a provider, verify your identity, and generate a one-time or reusable virtual number.

    Focus on virtual card security—choose strong authentication, set spending limits, and enable alerts. Decide on funding methods before you need the card so payments don’t fail.

    • Pick a trusted issuer and complete KYC quickly
    • Choose between single-use or multi-use virtual numbers
    • Link funding methods: bank account, debit/credit, or wallet
    • Set limits, alerts, and an expiration for added security

    After funding, confirm the card is active and test a small authorization before larger purchases.

    Use Virtual Cards in France (In-Person & Online)

    Now that you’ve created and funded a virtual card, you’ll want to use it effectively in France for both in-person and online purchases.

    For in-person payments, add the card to your phone’s digital wallet integration and use contactless taps where accepted; vendors often prefer NFC over chip-and-PIN, but keep a backup physical card handy.

    Online, enter the virtual card number at checkout or use the wallet’s autofill to avoid manual errors.

    Prioritize virtual card security: enable transaction alerts, set single-use or merchant-locked options, and freeze the card instantly if something looks off.

    Keep receipts and check statements promptly to catch merchant errors or unauthorized charges.

    Using these practices, you’ll minimize fraud risk and avoid unnecessary fees while traveling.

    Virtual Cards and Currency Conversion: Euros vs. Home Currency?

    When you use a virtual card in France, the currency choice—euros or your home currency—directly affects the exchange rate and any dynamic currency conversion (DCC) fees you might pay.

    So pick the option that minimizes total cost. You should usually accept charges in euros to avoid merchant DCC markups; your card issuer’s rate plus any foreign transaction fee (often waived with travel-friendly virtual cards) is often cheaper.

    Before paying, check virtual card comparisons and issuer rules for currency conversion strategies. Also confirm whether your virtual card locks a rate or uses real-time conversion.

    • Choose euros to avoid merchant DCC markups
    • Check issuer exchange rates and fees first
    • Compare virtual card comparisons for travelers
    • Consider locking a rate if offered

    What to Do If a Merchant Adds an Extra Fee

    If a merchant adds an extra fee at checkout, don’t just accept it—ask why and request an itemized receipt so you can see whether it’s a legitimate service charge, a card processing fee, or an unauthorized markup.

    Check the merchant policies posted or ask staff which charges are standard. If the fee seems improper, refuse the charge and offer alternate payment options like your virtual card or cash.

    Document everything: take photos of the receipt, note names, and keep timestamps.

    Contact the merchant’s customer service immediately to explain and request a refund. If that fails, file a fee dispute with your card issuer, supplying the itemized receipt and communication records.

    Persist until the charge is corrected or reversed.

    Pre-Trip Safety Checklist and Limits for Virtual Cards

    Checklist and limits matter: before you travel, review your virtual card settings, daily and per-transaction limits, and expiration dates so you won’t be surprised at checkout.

    You’ll want a quick pre-trip budgeting check to set realistic limits, and confirm card security features like CVV, merchant locks, and one-time-use options.

    Lock or pause cards you aren’t using, and note how to contact your issuer from abroad.

    • Set daily and per-purchase limits that match your itinerary
    • Enable merchant or category restrictions to reduce fraud risk
    • Pick single-use or short-expiry virtual numbers for high-risk purchases
    • Save issuer emergency contact and international support details

    These steps keep spending predictable and strengthen card security while you’re in France.

    Frequently Asked Questions

    Can Virtual Cards Be Used for Train Ticket Machines in France?

    Yes — you can sometimes use virtual cards at French train ticket machines, but compatibility varies. You’ll want to check train ticketing options beforehand, carry a backup physical card, and enable contactless or mobile wallet features.

    Will French Cafés Accept Virtual Cards for Contactless Payments?

    Yes — like rain on a terrace, you’ll often tap and go: French payment trends favor contactless, and many cafés accept virtual cards via NFC or phone wallets; check café payment methods, since smaller places might still prefer cash.

    Do Virtual Cards Work With Ride-Share Apps Like Uber in France?

    Yes — you can usually add virtual cards to ride-share apps in France; they offer ride share compatibility and strong payment security, so you’ll tap into seamless bookings while keeping your real card details hidden from drivers and services.

    Can I Add Travel Insurance Coverage Through a Virtual Card?

    Imagine a safety net unfolding; yes, you can sometimes add travel insurance options to bookings paid with virtual cards, but you’ll hit virtual card limitations—check issuer policies, coverage fine print, and booking channel acceptance before relying on it.

    How Do Virtual Cards Handle Refunds From French Merchants?

    Virtual cards handle refunds like regular cards: you’ll receive reimbursements through the issuer, but timing depends on the refund process and merchant policies; you’ll need to provide transaction details, and disputes go through your card issuer if needed.

    Final words

    Think of your virtual card as a pocket-sized guidebook on cobblestone streets: it whispers the local language (euros), avoids the tourist traps (foreign transaction fees), and slips between busy vendors without drawing attention. You preload it, set spending limits, and carry it like a slim passport—ready when a café or online seller asks for payment. Travel light, trust the guidebook, and let small digital tools keep your trip smooth and fee-free.